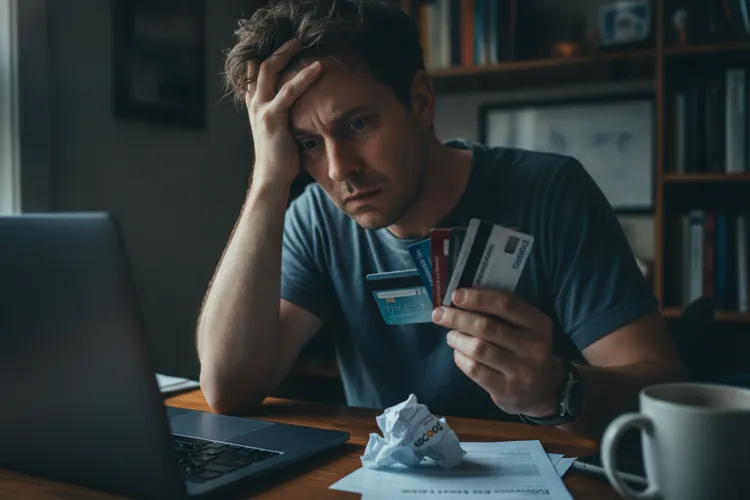
A new survey found that 72% of credit cardholders have paid down their debt, only to see their balances rise again, while 58% report significant stress or anxiety related to what they owe.
Shame, repeated financial setbacks, and debt-related stress can make it harder for consumers to make progress or seek help.
Consumers are encouraged to review what they can realistically afford, exploring hardship programs, and considering debt relief options when minimum payments aren't enough.
Paying down credit card debt can feel like a major accomplishment — until an unexpected expense or another tight month sends the balance climbing again. For many Americans, that cycle can make it difficult to feel like they're making any real progress, even when they're working hard to pay what they owe.
A new survey from Freedom Debt Relief found that 72% of U.S. credit cardholders have paid down their debt only to see it rise again. The financial strain can also take an emotional toll, with 58% reporting significant stress or anxiety related to their debt.
ConsumerAffairs spoke with Sean Fox, president of Freedom Debt Relief, who discussed why breaking the cycle can be so challenging, how debt-related stress can affect financial decisions, and what consumers can do to start working toward a more manageable financial future.
How the survey was conducted
Freedom Debt Relief conducted an online survey in July 2026, gathering responses from 1,006 U.S. adults who carry a credit card balance from one month to the next.
Respondents had an average age of 42, with millennials accounting for 51% of the group, followed by Gen X (24%), Gen Z (16%) and baby boomers (8%). The survey explored how often cardholders get caught in a cycle of debt, what makes repayment difficult, and how carrying a balance affects their financial and emotional well-being.
What the survey found
The results suggest that paying down credit card debt doesn't always translate into lasting progress. Overall, 72% of respondents said they've reduced their balances only to see them rise again, while 60% said they feel trapped in a cycle of credit card debt.
Financial strain was particularly pronounced among lower-income households: 69% of respondents earning less than $30,000 annually felt trapped, compared with 42% of those earning six figures.
The survey also highlighted gaps in financial knowledge and the emotional toll of carrying debt. Only 29% of respondents knew the exact interest rate on their highest-balance credit card, and 58% said their debt caused significant stress or anxiety.
Nearly half (47%) felt embarrassed or ashamed about how much they owed. Despite these challenges, 57% had never considered a debt relief program, suggesting that many cardholders may be struggling to find a path forward.
The psychological barriers to paying down debt
Fox touched on the idea of shame and how that can be a driver to continuous credit card debt.
“Shame can make people treat debt as a reflection of their character,” he said. “They feel embarrassed about what they owe or believe they should fix it themselves, so they delay asking for help even when their payments aren’t making a meaningful difference.”
Another factor: worn down confidence from repeated setbacks. “When months of repayment are erased by one unexpected expense, people can stop believing they’ll ever get ahead,” Fox said. “Making the minimum payment becomes a way to get through the month rather than a plan to get out of debt.”
A constant cycle of stress
While debt alone can feel like a burden, Fox explained that consistent credit card debt can also impact how consumers feel about making other financial decisions. One bad decision can sometimes feel like every choice after that will be catastrophic.
“Debt stress can make it harder to weigh options because so much attention is consumed by the immediate pressure of paying bills,” Fox said. “People may focus on whichever choice gets them through the next due date, even if it leaves them with higher costs or a payment they can’t sustain.
“Anxiety can also make people put their head in the sand and ignore important account details. Checking a balance or opening a statement can feel overwhelming when they don’t have the money to address it. That can delay action until their choices are more limited.”
Breaking the cycle
Low-income consumers were the most likely to feel trapped by a never ending cycle of credit card debt. Fox offered some advice for those trying to break out of that trap.
“For someone with limited income, a debt repayment plan has to leave enough for daily life,” he explained. “If making a payment means putting groceries back on the card, that payment isn’t producing lasting progress. Start with take-home income, subtract essential, fixed expenses, and determine what you can consistently afford to put toward debt.
“If that amount won’t cover the minimums, ask your card issuers about hardship programs that could reduce interest or payments. But if the balance itself is more than you can realistically repay, it’s worth exploring an approach that addresses the amount owed.”
Fox also recommends that consumers look into debt settlement, which can be particularly helpful for people facing financial hardship.
“Reducing the debt itself can put getting out of debt within reach when cutting expenses and making minimum payments haven’t been enough,” he said. “A professional assessment can help you understand whether that approach fits your circumstances and what an affordable program could look like.”
Ask for help
Fox’s biggest piece of advice: don’t wait to ask for help.
“You don’t have to wait until you miss a payment to ask for help,” he said. “The purpose of seeking advice is to understand what could work from here, without being judged for how you got here.
“Seeking help can make debt feel less isolating and give people a clearer sense of what they can do next.”