
Balance transfer vs. debt consolidation overview
A balance transfer is one form of debt consolidation, but the two aren't interchangeable.
A balance transfer moves multiple debts to a single credit card, often with a temporary 0% or low introductory rate. Debt consolidation is broader and can involve a personal loan, home equity loan or HELOC, usually with a fixed interest rate and repayment schedule.
The right option depends largely on how much you owe, how quickly you can repay it and what interest rate you qualify for. Balance transfers may be useful for smaller balances you can pay off during the promotional period, while consolidation loans may be better suited to larger balances or borrowers who need predictable monthly payments.
Both options can simplify repayment and potentially reduce interest costs, but neither is a solution by itself. Balance transfers come with fees and higher rates after the promotional period, while consolidation loans may include origination or other fees. Before choosing, compare rates, fees, repayment timelines and your ability to stick to a debt payoff plan.
What is a balance transfer?
A balance transfer is a way to consolidate debt from two or more sources into a loan agreement with a single lender. You transfer debts onto a single credit card, ideally with a lower interest rate so you can pay it off faster.
Sign up for automated payments after making a balance transfer to improve your credit score.
Many lenders offer a 0% interest balance transfer card. You’ll be charged no interest for a limited period, allowing you to pay down debt without incurring additional interest. You may also be able to lower your payment or shorten your repayment term.
“If you're attacking a pile of credit card debt, transferring it to a new card with a 0% or very low introductory interest rate can be a great option to make headway,” advised Zachary Mineur, chief investment officer at Independence Square Advisors in King of Prussia, Pennsylvania.
For example, say you have $25,000 in debt at a 22% interest rate. You sign up for the U.S. Bank Shield Visa Card and receive 0% interest for 21 months. By transferring your debt to this credit card, you can save over $8,700 during the introductory period alone. The card then changes to a set interest rate based on factors like your credit score.
“The promotional 0% window is the entire value,” explained Nick Avila, founder of United Debt Relief in San Diego, California. “For a defined stretch, usually somewhere between twelve and twenty-one months, every dollar you pay attacks principal instead of interest.”
However, it’s best to pay off as much of your debt as possible during the introductory period, so you maximize card benefits and shorten the repayment term. Regular, timely payments will also help improve your credit score so that you can qualify for better terms in the future.
“Balance transfers can be a great tool to stop the bleeding while you are working a debt payoff plan, but only if you are actually committed to paying it off,” said Mineur. “Otherwise, you are just kicking the can down the road and not improving the situation.”
After you pay off your debt, you can continue using the card like a normal credit card, which includes earning and redeeming any card rewards.
Balance transfers can be a great tool to stop the bleeding while you are working a debt payoff plan, but only if you are actually committed to paying it off.”
However, this can also present a risk, warned Michael McAuliffe, president of Family Credit Management in Chicago, Illinois. “Balance transfers only make sense if you’re 100% sure you can pay the full amount off before the promotional rate ends because once that window closes, credit cards are one of the most expensive ways to borrow money and you’ll likely be stuck with an interest rate that’s just going to make your situation worse.”
Ashley Morgan, a bankruptcy attorney in Virginia, outlined the ideal candidate. “Balance transfer cards can be a great option for someone who is still financially stable, has decent credit and has a realistic plan to pay off a meaningful portion of the balance during the promotional period,” she said.
Balance transfer cards pros and cons
There are both pros and cons to a balance transfer credit card that you should weigh to determine if it is the right solution for you.
Pros
- Simplifies repayment: A balance transfer credit card consolidates multiple debts into a single card, so you only have to make one monthly payment to a single lender.
- Saves on interest: There is a promotional period with low or 0% interest, allowing you to save on interest during that time.
- Allows ongoing use: A balance transfer credit card includes a line of credit for use during and after repayment.
- Provides rewards: Many balance transfer credit cards include special rewards, such as cash back, gift cards and travel credits.
- Extends payment terms: By combining your debt onto a balance transfer credit card, you have extra time to pay off your debt.
Cons
- Fees apply: These can include balance transfer fees, which typically range from 3% to 5%. There may also be annual fees and prepayment penalties if you pay your debt off early.
- High rates after promotional period: The low or 0% interest rate is only temporary, and then the card will likely move to a higher interest rate. For example, if you choose the Discover card, interest rates can climb as high as 26.49% after the promotional period.
- Potential impact on credit: Applying for a new balance transfer credit card can temporarily affect your credit score due to the hard inquiry. However, regular, timely payments can help improve your credit over time.
- Terms vary: While an issuer may advertise a minimum interest rate, there is no guarantee that you will qualify. Lenders will evaluate your income, debts and credit history before approving you for a card.
» LEARN: What is a hard inquiry?
What is debt consolidation?
Debt consolidation combines multiple high-interest debts into a low-interest loan with a single lender. You make a fixed payment to your lender directly, and it distributes the payment among your creditors as appropriate.
“A loan gives you one payment, one due date and one payoff date,” explained Morgan. “For a lot of people, the simplicity of a debt loan takes away some of the stress. The fixed payment and simple interest also make it much easier for most people to budget.”
A balance transfer credit card is one form of debt consolidation, but there are other types, too.
Debt consolidation is available as both secured and unsecured loans.
Secured debt consolidation loan
With a secured debt consolidation loan, you provide collateral that the lender can seize if you default on your loan. This may be a home, a vehicle or even a retirement account. An example is a home equity loan or HELOC.
Unsecured debt consolidation loan
Collateral is not always required, however. Unsecured debt consolidation loans are available, albeit at a higher interest rate. These loans are typically approved as personal loans.
A debt consolidation loan typically has a fixed interest rate and term, unless you opt for a revolving line of credit, such as a HELOC. This keeps your monthly payment the same, further simplifying repayment.
You can get a debt consolidation loan from most banks and credit unions, as well as online loan companies.
Debt consolidation loans pros and cons
While helpful, debt consolidation has pros and cons worth considering.
Pros
- Convenience: With debt consolidation, all of your debts are combined into a single bill, so you only have one creditor to pay each month.
- Lower interest rates: There are several debt consolidation options you can explore to find the lowest interest rate. These are often lower than credit card interest rates.
- Longer repayment term: When you consolidate your debt, you extend your repayment timeline, giving you more time to manage it.
- More options: Debt consolidation comes in many forms, so you can also choose a personal loan, home equity loan or HELOC if you receive a better rate.
- Prequalification: You can prequalify for a personal loan so you don’t hurt your credit by applying for a loan you will not be approved for.
Cons
- Credit impact: Applying for debt consolidation can temporarily affect your credit, although making your payments consistently on time will boost your score over time.
- No introductory offer: Debt consolidation does not typically offer an introductory offer of low or 0% interest.
- Fees still apply: All types of debt consolidation carry certain fees, such as origination fees, prepayment penalties and late fees.
- Temptation to overspend: If you are not disciplined about your spending, you could end up further in debt with more damage to your credit score.
Should you choose to do a balance transfer or debt consolidation?
Both a balance transfer credit card and a consolidation loan help you combine multiple debts into a single account. But because they differ, you should take some time to consider your personal situation and financial goals to determine which debt repayment strategy works for you. For example:
If you want to pay off debt quickly, choose a balance transfer
A balance transfer credit card with 0% interest is a way to pay off debt while saving valuable dollars on interest that you can apply to your principal.
If you have a large balance, choose a consolidation loan
Balance transfer credit cards are typically limited in how much you can borrow, making other debt consolidation options, like a personal loan or home equity loan, more appropriate.
If you want predictable payments, choose a consolidation loan
A debt consolidation loan can give you a set repayment timeline with fixed monthly payments for easy budgeting.
If you want the lowest possible interest cost, it depends on your timeline
If you pay off your debt quickly, a 0% interest balance transfer credit card could be the better bet. However, if you need a longer repayment period, a personal loan or a HELOC can provide the extra time you need.
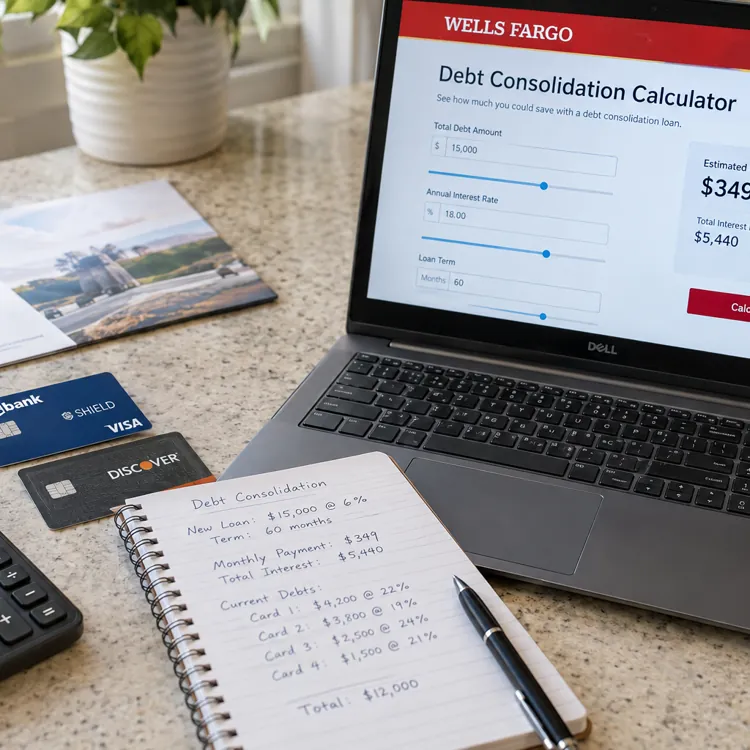
Be sure to run the numbers before making a decision. Many lenders, such as Wells Fargo and Charles Schwab, offer a debt consolidation loan calculator that you can use to test out different options. You can then compare a balance transfer with debt consolidation to see which one will work best for your debt.
“It only helps if you qualify for a rate meaningfully below what you are already paying,” said Avila. “A loan at a similar rate just reshuffles the debt.”
Morgan agreed. “Both balance transfers and debt consolidation loans can absolutely work, but only if those actions are part of a larger financial plan,” she said. “The right option for you depends on why the debt accumulated in the first place and whether the budget actually works.”
» MORE: Does debt consolidation hurt your credit?
Balance transfer credit cards vs. debt consolidation loans
When choosing between a balance transfer credit card and a debt consolidation loan, it's important to compare the key features of each. The table below highlights the main differences to help you decide which option works best for your situation.
| Balance transfer credit card | Debt consolidation loan | |
| Best for | Smaller debt | Larger debt |
| Introductory 0% offer | Yes | No |
| Line of credit | Yes | Yes, with HELOC |
| Credit limit | Low | High |
| APR (after promo period) | Typically higher | Typically lower |
| Credit requirements | Good to excellent credit | Flexible, depending on lender |
| Repayment timeline | Limited promotional period | Fixed pay-off date |
Avila summed it up. “Which one is best? Neither, universally.”
“The deciding question is simple: Can you realistically clear this balance inside the promotional window?”
Your answer will help determine whether a balance transfer or other type of debt consolidation is the right choice for you.
FAQ
What is the downside of balance transfer?
The downsides of a balance transfer include high interest rates after the promotional period and fees that reduce the impact of your payments. It may also temporarily affect your credit when you apply for a balance transfer credit card.
Is a balance transfer better than a debt consolidation loan?
A balance transfer is often better than a debt consolidation loan when you want to pay off a smaller debt fast.
What happens after a balance transfer promotional period ends?
After the promotional period, the interest rate on a balance transfer credit card generally increases to a higher rate going forward.
Does debt consolidation hurt your credit score?
Yes, debt consolidation may temporarily hurt your credit score when you apply, but making regular, on-time payments will help improve it. However, if you fail to make your payments, you risk further damage to your score.
Article sources
ConsumerAffairs writers primarily rely on government data, industry experts and original research from other reputable publications to inform their work. Specific sources for this article include:
- Discover Financial Services, "Balance Transfer vs. Debt Consolidation." Accessed Aug. 12, 2026.
- U.S. Bank National Association, "U.S. Bank Shield Visa Card." Accessed Aug. 12, 2026.
- Harvard Federal Credit Union, "Debt Consolidation Loan or Balance Transfer? Know Your Options." Accessed Aug. 12, 2026.
- Discover, "Discover it Cash Back." Accessed Aug. 12, 2026.
- Wells Fargo Bank, "Debt Consolidation Calculator." Accessed Aug. 12, 2026.
- Charles Schwab, "Debt Consolidation Calculator." Accessed Aug. 12, 2026.