
Should you get rid of your monthly car loan?
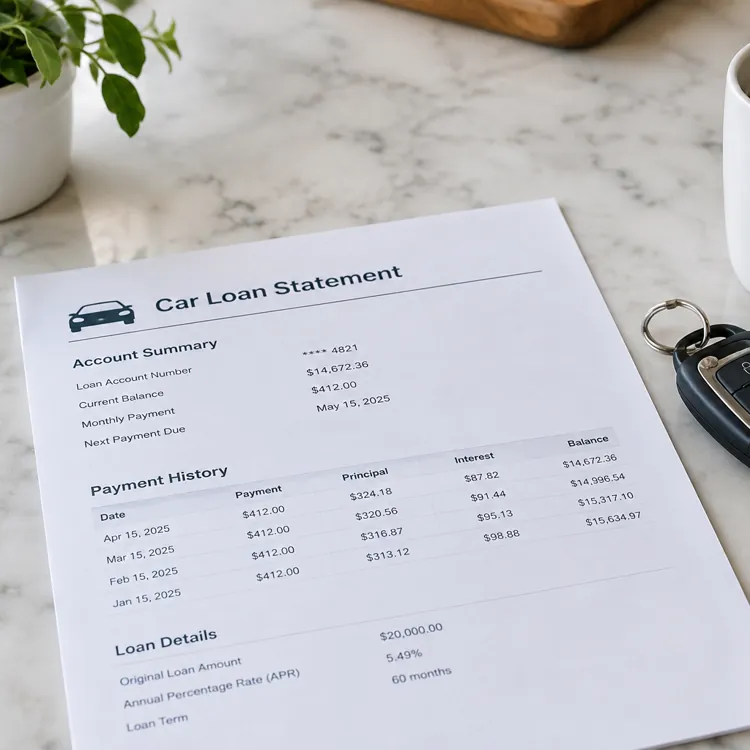
Before deciding to pay off your car loan early, factor in your emergency savings, other debt and the interest rate (fixed vs. variable) of your loan. However, before you commit to a payoff plan, review your loan documents or contact the lender to confirm there’s no prepayment penalty.
When paying off early makes sense
Paying off a loan early can save you money, as the shorter the loan term, the less interest you’ll pay. It may make sense to pay off your car loan early if you’ve earned extra income, such as a bonus or higher commission, and your loan has a high or variable interest rate. Variable rates can make monthly payments unpredictable, so paying off the loan early may help reduce stress.
When keeping the loan is better
In some cases, sticking with the current payment plan may be the best option. Although it’s uncommon, if your prepayment penalty would cost more than the interest you'd save, you may want to keep the loan. You also don’t want to wipe out a savings account or emergency fund in order to pay off a loan early.
How interest rate changes the decision
Consider the loan’s interest rate and compare it with the returns you could earn by investing the funds elsewhere. For example, paying off the loan early may not make sense if you can invest the money at a higher rate than the interest you pay. For example, if your investment funds earn 10% per year while the loan charges 4% interest, investing may be the better option.
Also, compare the car loan interest rate with any other debt you currently have. It may be better to pay off high-interest debt, like credit cards, before the car loan.
Car loan early payoff pros and cons
The main benefits of paying off a loan early are saving on interest and freeing up cash to use elsewhere. It also eliminates the risk of being upside down, meaning your car is worth less than the loan balance. Paying off debt also improves your debt-to-income ratio, which lenders use to determine how much you can afford to borrow.
The main con is potential prepayment penalties. Another drawback is reduced cash in your emergency savings or investment accounts. Paying off debt may also cause your credit score to dip slightly, usually by a few points. This is only temporary, and your score should recover in just a few months, but it may affect any loan applications during that time.
Pros
- Interest savings
- Frees up cash flow
- Reduced upside-down risk
- Improved debt-to-income ratio
Cons
- Potential prepayment penalties
- Reduced emergency savings
- Temporary dip in credit score
» RELATED: Buying a car with bad credit
Prepayment penalties and payoff fees
Some lenders charge prepayment penalties to recoup lost interest income, which could cost 1% to 2% of your remaining loan balance. If the lender charges a penalty, it must be stated upfront in the loan documents you signed when you purchased the car.
Here are some items to verify before paying off your loan:
- Prepayment penalty: If you can’t find the original loan documents, you can contact the lender for this information.
- Simple vs. precomputed interest: Simple interest, which is used on most car loans, is calculated daily on the remaining balance. Still, check that the loan doesn’t use precomputed interest, which is calculated upfront and added to the principal when you first take out the loan. If it does, paying off the loan early may offer no benefit.
- Payoff quote expiration: Ask for a payoff quote, which shows the exact balance you need to pay, including per diem (per day) interest. These quotes are usually valid for seven to 10 days, so you must pay that balance within that time frame or it expires.
- Lien release timeline: A lien is the lender's legal claim to your vehicle until you pay off the loan. Ask how long it takes for the lien to be released after your payment clears. This usually happens within 30 business days.
- Title fees: The process varies by state, but once the lender releases the car’s title, you’ll need to pay a fee to transfer it into your name. The fee typically costs $30 to $75, depending on the state.
- Auto-pay cancellation: Ask about the process for canceling auto pay. Lenders require prior notice, usually at least three business days before the payment’s draft date, to successfully cancel electronic payments.
How to pay off your car loan
A lump-sum payment isn't the only way to pay off your car loan faster. You can use other strategies, and the total interest you save depends on when you make extra payments.
Other strategies to pay off a loan faster include:
- Extra principal each month: Pay extra each month toward principal, and tell your lender that’s where the money should go; otherwise, it may count as an early payment on next month’s bill. You’ll pay off the loan sooner, pay less interest and build equity faster, so you’re less likely to owe more than the car is worth.
- Biweekly payments: Car payments are typically due monthly. However, if you split the monthly payment in half and make biweekly payments (every two weeks), you’ll make one extra car payment each year. Just be sure that you have payments set up so that you are at least making one full car payment monthly by the due date.
- Refinance: Refinancing your car loan for a lower rate and shorter term can help you pay it off sooner, possibly without a higher monthly payment than you have now. Keep in mind that lenders may charge loan origination fees, so check whether the interest saved outweighs the fees.
» COMPARE: Top car loan companies

FAQ
Is there a downside to paying off a loan early?
Paying off your car loan early can have drawbacks. The lender may charge prepayment penalties, and your credit score may temporarily drop a few points.
Why did my credit score drop after paying off my car?
Your credit score may drop only a few points after paying off debt because your credit mix temporarily changes. Credit bureaus use a combination of credit mix (types of credit), credit history, payment history, new inquiries and credit utilization ratios to calculate your credit score.
How much can I save if I pay off my car loan early?
Depending on your interest rate, loan term and loan amount, you could potentially save thousands in interest by paying it off early. Use an online payoff calculator to enter your remaining balance and interest rate and see how much you can save.
Can you pay off a car loan early without a penalty?
Typically, lenders don't charge prepayment penalties on car loans. However, always check your loan paperwork or contact your lender for those details.
Bottom line
Paying off a car loan can be a smart financial decision if you have the available funds and your lender doesn’t impose prepayment penalties. Before you do, compare the interest rate of your car loan to any other outstanding debts. You’ll want to pay any with higher interest rates first.
Article sources
ConsumerAffairs writers primarily rely on government data, industry experts and original research from other reputable publications to inform their work. Specific sources for this guide include:
- Citizens Bank, "What debt-to-income ratio do you need for a mortgage?" Accessed Nov. 18, 2026.
- Alliant Credit Union, "Will paying off an auto loan help or hurt my credit score?" Accessed Nov. 18, 2026.
- National Debt Relief, "What Is a Loan Prepayment Penalty and How It Works." Accessed Nov. 18, 2026.
- Consumer Financial Protection Bureau, "What's the difference between a simple interest rate and precomputed interest on an auto loan?" Accessed Nov. 18, 2026.
- CarsDirect.com, "What’s an Auto Loan Payoff Quote?" Accessed Nov. 18, 2026.
- OneMain Financial, "What Is a Lien on a Car and How Does It Work?" Accessed Nov. 18, 2026.
- General Motors Financial Company, "Title Release." Accessed Nov. 18, 2026.
- Consumer Financial Protection Bureau, "How do I stop automatic payments from my bank account?" Accessed Nov. 18, 2026.
- JPMorgan Chase Bank, "Should I consider paying my car loan off early?" Accessed Nov. 18, 2026.
- JPMorgan Chase Bank, "Pros and cons of refinancing an auto loan." Accessed Nov. 18, 2026.
- Equifax, "Why Your Credit Scores May Drop After Paying Off Debt." Accessed Nov. 18, 2026.