Twelve percent of workers facing higher health premiums reduced retirement contributions, LIMRA found.
Among Gen Z employees facing increases, 21% cut retirement savings.
Most workers spend less than an hour reviewing and enrolling in workplace benefits.
Higher health insurance premiums are prompting some Americans to sacrifice retirement savings as they struggle to balance competing financial demands.
LIMRA's 2026 Benefits and Employee Attitude Tracker (BEAT) Study found that more than three-quarters (77%) of employees enrolled in workplace medical coverage saw their premiums increase in 2026, including 17% whose premiums rose by more than 10%. About half of those facing higher premiums changed their spending or benefits decisions in response:
20% cut back on everyday spending.
12% reduced retirement savings contributions.
16% reduced spending on other employee benefits.
16% switched to a less expensive medical plan.
9% chose not to enroll in other benefits.
Younger workers were the quickest to react. Nearly three in four Gen Z employees whose premiums increased took some action, and 21% cut their retirement contributions — the workers with the most time to benefit from long-term savings growth.
"As consumers evaluate their healthcare options during open enrollment, it's important to recognize the connection between healthcare decisions and retirement readiness. Increasing healthcare costs can put pressure on household budgets today while making it more challenging to save for the retirement people envision tomorrow," said Kimberly Landry, Research Director, Workplace Benefits Research at LIMRA and LOMA.
Open enrollment decisions can affect household finances for years, yet LIMRA found that 63% of workers spend less than an hour reviewing their options and enrolling, and more than a quarter spend less than 30 minutes.
Growing financial strain
Those decisions are being made under financial strain. Nearly half of workers (49%) are very or extremely concerned about healthcare and health insurance costs, and 57% are more worried about those costs than they were a year ago. Forty-two percent are concerned about their ability to save enough for retirement. And 55% would need to borrow or finance an unexpected $2,000 medical bill not covered by insurance — or could not pay it at all.
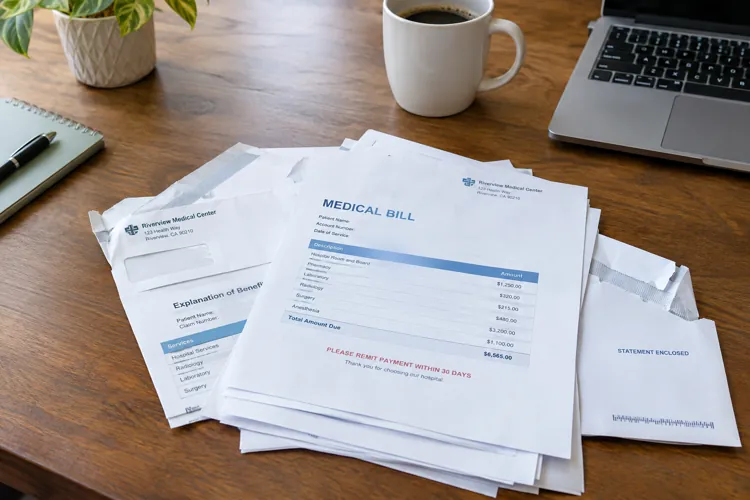
The findings also reveal limited financial breathing room: 55% of workers would need to borrow, finance or be unable to pay an unexpected, uninsured $2,000 medical bill.
For open enrollment, LIMRA recommends comparing deductibles, prescription benefits, provider networks and potential out-of-pocket expenses alongside premiums. Workers who must reduce retirement contributions should try to preserve their employer match.
The online survey included 4,052 U.S. workers ages 18–64 and was conducted in January 2026.