Congress has given final approval to the Common Cents Act, formally ending production of pennies for general circulation.
Existing pennies aren’t being canceled, as they remain legal tender and consumers can continue spending them.
As pennies become harder to find, businesses will be able to round cash purchases to the nearest nickel; purchases made by credit card, debit card, and other non=cash methods can still be charged to the exact cent.
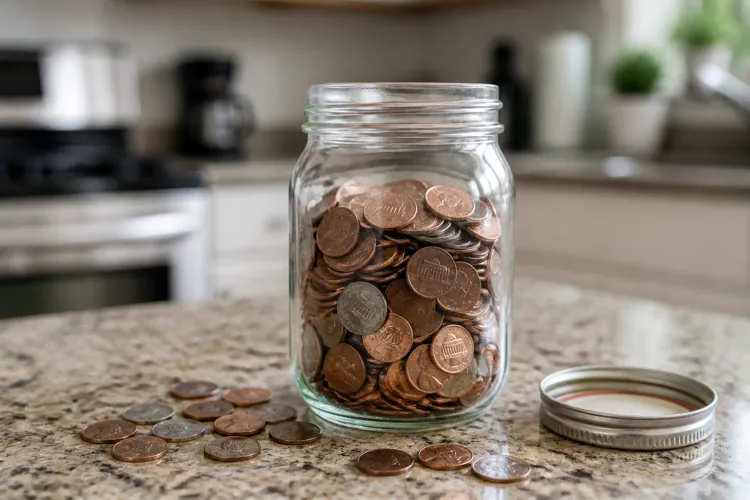
The penny’s days at the U.S. Mint are over, but that doesn’t mean the pennies sitting in your change jar have suddenly become worthless.
Congress has given final approval to the Common Cents Act, legislation that formally directs the Treasury Department to stop producing one-cent coins for general circulation. The Senate approved the measure Sept. 28 after House passage, sending it to President Trump, who supports the legislation.
In practice, penny production had already ended. The federal government stopped manufacturing new pennies in 2025, as the cost of making the coin climbed far above its face value. The Treasury says producing a penny had risen to 3.69 cents and estimates stopping production will save about $56 million annually in material costs.
The legislation addresses one of the biggest practical questions created by that decision: What happens when a cash purchase comes to $10.22 but the store doesn't have pennies to make change?
Cash purchases can be rounded
The Common Cents Act establishes a framework allowing cash transactions to be rounded to the nearest five cents when exact change isn't available.
Under the system, a cash total ending in 1, 2, 6, or 7 cents can be rounded down to the nearest nickel. A total ending in 3, 4, 8, or 9 cents can be rounded up.
For example: A $10.21 cash purchase could become $10.20, while a $10.24 purchase could become $10.25. A $10.26 purchase could become $10.25, while $10.29 could become $10.30.
Importantly, the federal legislation permits this type of rounding but does not require every transaction to be rounded. Businesses that have pennies available can continue making exact change.
The rounding also applies to the final transaction total, rather than individual prices. A retailer would not, for example, have to change a $2.99 price tag to $3.
Cards will still be charged to the penny
Consumers who rarely use cash may notice virtually no difference.
Credit cards, debit cards, checks, and electronic payments can continue to be processed to the exact cent. A $19.98 purchase charged to a credit card would still cost $19.98 rather than being rounded to $20.
The Treasury has similarly recommended that rounding should apply only to cash transactions, and taxes and other charges should be calculated before the final cash amount is rounded.
That distinction could become increasingly noticeable at stores. The amount displayed on the register might be $24.97, for example, but a customer paying cash could pay $24.95 if the retailer is using rounding. However, a customer using a card would pay exactly $24.97.
Don't throw your pennies away
Perhaps the most important point for consumers is that the penny isn't being demonetized.
The Treasury says roughly 114 billion pennies remain in circulation, and the Federal Reserve can continue recirculating them. Existing pennies retain their face value and their status as legal tender.
Consumers therefore don't need to rush to cash in jars of pennies before a deadline. They can continue spending them, and financial institutions can continue accepting penny deposits, although banks may have their own rules requiring large quantities of coins to be rolled or wrapped.
The Treasury has actually encouraged Americans to spend the pennies they already have, which could keep more coins circulating and make the transition easier for businesses.
Will rounding cost consumers money?
In an individual transaction, it could — by as much as two cents. But another transaction could save the consumer the same amount.
The Treasury argues that symmetrical rounding should prevent either shoppers or retailers from gaining a systematic advantage because some purchases round up and others round down. It says there should therefore be no overall effect on consumer prices from rounding.
The legislation also calls for federal officials to examine how the transition affects groups that rely more heavily on cash. The Federal Reserve's required planning includes an assessment of penny-supply disruptions and rounding on low-income communities, older consumers, and people who are unbanked or underbanked.
For consumers, the simplest way to think about the change is this: Prices can still be stated to the penny, electronic payments can still be made to the penny, and the pennies you already own are still worth a penny.
What is disappearing is the government's production of new ones. Over time, as the existing supply dwindles, paying with cash is increasingly likely to mean rounding the final bill to the nearest nickel.