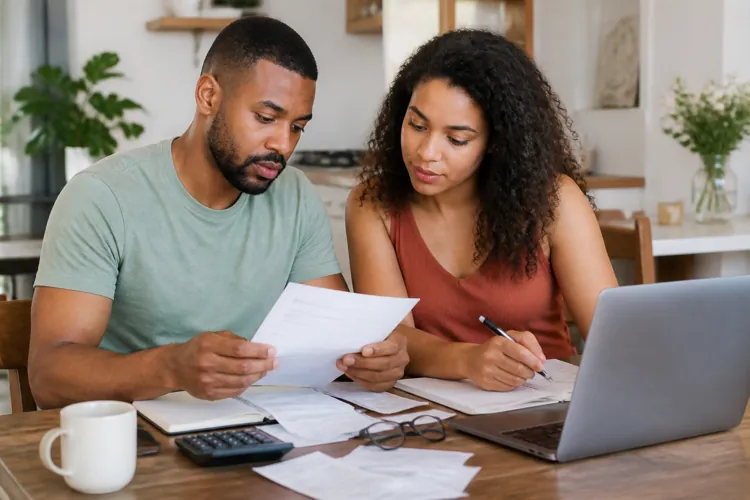
43% of homeowners say they’re “house rich and cash poor,” even as home values continue to rise.
Rising housing costs are forcing homeowners to make financial sacrifices, including cutting discretionary spending and reducing emergency and retirement savings.
Experts say homeowners should plan for less obvious costs, including changing property taxes, insurance premiums and ongoing home maintenance.
Owning a home is often seen as a major step toward financial security. But for many homeowners, rising housing costs are making it harder to enjoy that sense of stability. Even as their homes increase in value, many are finding themselves with less money available for everyday expenses, savings and major purchases.
A new study from AmeriSave highlights just how common this “house rich, cash poor” dilemma has become, with homeowners making financial sacrifices to keep up with the cost of owning a home.
ConsumerAffairs spoke with Jerrie Giffin, VP of Sales at AmeriSave, to learn more about what’s driving the trend and what it means for homeowners’ financial well-being.
Methodology
AmeriSave surveyed 1,000 U.S. homeowners through an online poll to better understand how people are managing rising housing costs and how those expenses are affecting their financial well-being.
The survey asked about homeowners’ financial situations, changes in housing costs compared with income, spending and savings sacrifices, and whether they had considered using home equity to access cash.
Results were also analyzed by generation, household income, and gender. The findings are based on self-reported responses, and percentages may exceed 100% when respondents could select multiple answers.
Key findings
The results highlight the gap between growing home values and everyday financial security.
Here’s a look at the key findings from the survey:
43% of homeowners said they feel “house rich and cash poor”
66% said their home has increased in value, but they don’t feel financially better off.
45% said housing expenses have outpaced their income.
53% have cut back on discretionary spending, such as vacations and dining out.
52% have scaled back major purchases.
Nearly half (49%) have reduced contributions to emergency savings.
37% have cut back on retirement savings.
24% have taken on extra work to cover housing costs
23% have used credit card debt to help pay for them.
Know your long-term goals
With nearly half of homeowners surveyed reducing their contributions to emergency savings accounts, Giffin encourages consumers to be clear about their long-term savings and financial goals.
“It's important to take a step back and set your long term goals,” he said. “Many homeowners love having equity until they can't tap into it due to their income / liquid assets. It’s never been more important to set real expectations for what you need financially.”
Escrow: The hidden cost of homeownership
Whether you’re a current homeowner or thinking of becoming a first-time owner, Giffin says that understanding your home’s specific escrow account is one of the most important lessons.
“So many homeowners don’t fully understand how their taxes and insurance can change and mold their payments,” he explained. “I see many homeowners get priced out of homes due to escrow increases.
“Do your research on the home and the area and be prepared for any potential tax/insurance hikes in your area.”
One step at a time
Once you’re in a home, maintaining it comes with its own set of costs. However, you don’t need to fix everything immediately!
Giffin recommends taking things one step – and one month – at a time.
“I live by a once-a-month rule,” he said. “I don’t remodel the house all at once. I find one maintenance piece I can do every month that ensures I don’t run into major issues down the road but doesn’t break the bank today.”