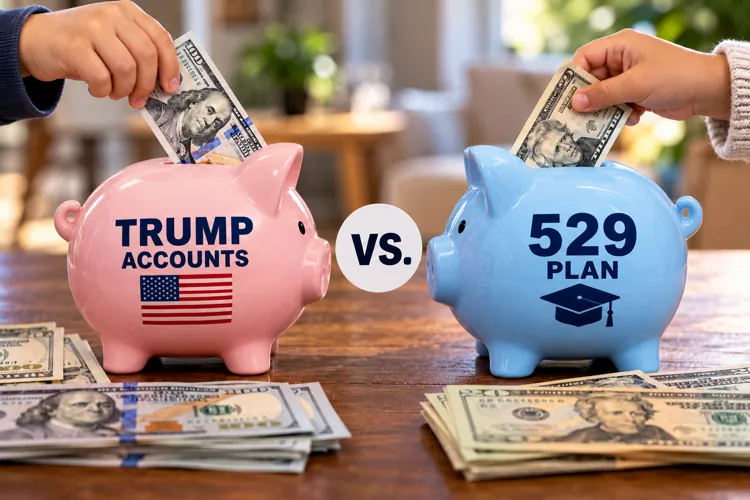
Free money for eligible newborns: Children born between January 1, 2025, and December 31, 2028, can qualify for a one-time $1,000 federal contribution to a Trump Account.
Different tax benefits: Trump Accounts offer tax-deferred investment growth, while 529 plans generally allow tax-free withdrawals for qualified education expenses.
You don't have to choose just one: Families can maintain both accounts, using them for different financial goals.
Want to give your child or grandchild a financial boost or start the process of saving for college? A new savings option could help you do just that.
Trump Accounts, created under the 2025 federal tax law, are now available to eligible children under 18. And for millions of young Americans, the federal government is offering a flat $1,000 to help start investing.
But here's where things get interesting. For years, 529 college savings plans have been a popular way for families to put money aside for education. Now parents have another tax-advantaged account to consider.
So should you put money into a Trump Account, stick with a 529 plan, or use both? The answer depends largely on what you want the money to accomplish.
What exactly is a Trump Account?
A Trump Account is a special type of traditional individual retirement account (IRA) established for children. Parents or other authorized adults can open one for an eligible child under 18 who has a Social Security number.
The biggest attention-getter is the government's $1,000 contribution. But not every child qualifies for that money.
According to the IRS, the one-time deposit is available to eligible U.S. citizens born from January 1, 2025, through December 31, 2028.
Older children can still qualify for an account, but they don't qualify for that federal $1,000 contribution.
Pro tip: If you have a child born between 2025 and 2028, don't assume the $1,000 automatically arrives. Visit the official Trump Accounts website or use IRS Form 4547 to establish the account and request the federal contribution.
How does a 529 college savings plan compare?
A 529 plan is specifically designed to help families save for education costs. Parents, grandparents, and others can contribute money, choose investments from the plan's available options, and allow the account to grow over time.
The major attraction is the tax advantages. When withdrawals are used for qualified education expenses, including eligible college tuition, books, and certain room-and-board costs, the investment earnings generally come out tax-free.
And 529 plans have become more flexible. Depending on the expense and applicable rules, money can also be used for certain K-12 education costs, qualifying apprenticeships, student loans, and postsecondary credential programs.
Unlike Trump Accounts, 529 plans obviously don't come with a universal $1,000 federal contribution. However, some states do offer tax deductions, credits, or other incentives for contributing.
Trump Account vs. 529 plan: The biggest differences
Both accounts offer tax advantages, but they're designed for different purposes. Here's how they compare:
Who qualifies: Trump Accounts are available to eligible children under 18 with a Social Security number. A 529 plan can be opened for a beneficiary of any age.
Government seed money: Trump Accounts offer a one-time $1,000 federal contribution for eligible U.S. citizen children born between 2025 and 2028. Traditional 529 plans don't offer a universal federal contribution.
Annual contribution limits: Trump Accounts generally allow up to $5,000 in annual contributions during the special childhood period, with inflation adjustments beginning after 2027. The limits for 529 plans are substantially higher and vary by state.
Tax advantages: Trump Account investments grow tax-deferred, meaning taxes generally aren't due on investment gains while the money remains in the account. With a 529 plan, investment earnings can be withdrawn tax-free when used for qualified education expenses.
Using the money for college: Qualified 529 withdrawals are generally tax-free. Trump Account withdrawals may be taxable under traditional IRA rules, although qualifying education expenses can provide an exception to the 10% early-withdrawal tax.
Accessing the money: Trump Accounts generally restrict withdrawals before the calendar year the child turns 18. Money in a 529 plan can be withdrawn earlier for qualifying education expenses.
Investment options: Trump Accounts generally limit investments to qualifying low-cost U.S. stock index funds during childhood. A 529 plan offers investment choices selected by the plan, often including age-based portfolios.
Who controls the account: A Trump Account belongs to the child, with an adult custodian managing it during childhood. With a 529 plan, the account owner generally retains control over the money.
If your child skips college: Trump Account funds can remain invested for retirement. A 529 plan may allow you to change beneficiaries, pay for other qualified education expenses, or roll over up to $35,000 into the beneficiary's Roth IRA, subject to eligibility requirements.
What could $1,000 actually grow into?
Here's why starting early matters. Let’s suppose an eligible newborn receives the $1,000 federal contribution and the money stays invested for 18 years.
Assuming a hypothetical 7% annual return, compounded annually, here’s how that adds up:
Initial $1,000 only: Approximately $3,380 by age 18.
$1,000 plus $50 monthly: Approximately $24,800 by age 18.
$1,000 plus $100 monthly: Approximately $46,200 by age 18.
These numbers assume monthly contributions at the end of each month and don't account for taxes, fees, or inflation.
The lesson here is that even small contributions, made consistently over many years, can grow into a significant amount of money.
5 smart moves parents can make right now
Whether you're considering a Trump Account, a 529 plan, or both, here are five practical steps.
Check whether your child qualifies for the $1,000. If your child was born from 2025 through 2028 and meets the eligibility requirements, visit TrumpAccounts.gov and review the enrollment process.
Ask your employer about contributions. Some employers may offer qualifying Trump Account contributions. Check with human resources before assuming the only money going into the account will come from your family.
Compare your state's 529 tax benefits. Some states offer deductions or credits for contributions to qualifying plans. Visit Savingforcollege.com to compare plans, then verify any available tax benefits with your state.
Match the account to the goal. If the money is intended for college expenses, examine the 529's tax-free withdrawal rules. If the goal is building long-term retirement savings, consider the Trump Account's IRA structure and withdrawal restrictions.
Don't sacrifice your own financial security. Before making large contributions to a child's account, make sure you're addressing emergency savings, any expensive debt, and your own retirement needs.