
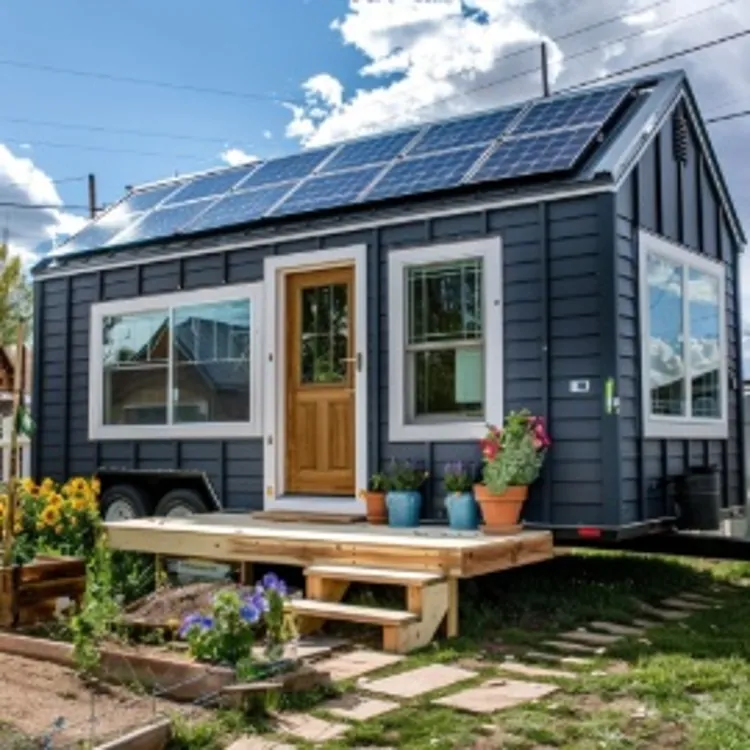
Tiny home financing hurdles
Tiny homes may be classified as a temporary structure and could face zoning challenges in many counties to qualify as a legal dwelling. In some municipalities, you may not be able to build a tiny home as a permanent home.
These legal challenges also mean that many lenders won’t offer a traditional mortgage for your tiny home, thanks to minimum loan amounts and requirements that can prevent borrowers from obtaining traditional home financing.
Whether your tiny home has wheels can also affect your financing options. In most cases, a tiny home on wheels or park model RV won't qualify for a traditional mortgage but may qualify for an unsecured personal loan or RV loan. The home's certification, such as RV Industry Association (RVIA), and how it's titled — as a vehicle, chattel or real property — can also affect how lenders evaluate it.
And even if your tiny home is built on a traditional poured foundation, you’ll still need to find a lender that offers loans on tiny homes.
In general, you’ll most likely need to find other financial options for the purchase of your tiny home.
Financing options for tiny homes
If you want to finance your purchase of a tiny home, you’re most likely not going to be able to obtain a traditional mortgage. Most lenders have loan minimums and won’t approve a traditional home mortgage on a nonpermanent dwelling. Here are a few financing options for tiny homes to consider instead:
Personal loans
A personal loan is an unsecured loan that you can obtain through a bank, credit union or online lender. You usually need a good credit score and stable income to be approved for a personal loan. Loan terms can be up to 12 years in some cases, but interest rates will typically be higher than a home loan. Additionally, personal loans may have maximum loan amounts that are insufficient for covering the entire cost of your tiny home, especially for more expensive projects.
Personal loans don’t usually use your tiny home as collateral — so your lender can’t take the home if you have trouble paying. You’ll pay for this flexibility with shorter loan terms, higher rates and no tax benefits.
RV loan
RV loans are a type of secured loan made for recreational vehicles. If you plan on living in an RV or if your tiny home has wheels, you can qualify for an RV loan. Most RV loans are secured to your tiny home, meaning your lender can take the tiny home or RV if you default on your payments.
RV loans are only for qualified recreational vehicles approved by the Recreation Vehicle Industry Association (RVIA) and that comply with U.S. Department of Transportation’s National Highway Traffic Safety Administration standards.
Builder financing
Some tiny home builders offer their own in-house financing, allowing you to get a loan directly from the company building your tiny house. These loans may be secured by your home (like a traditional mortgage), but the terms, rates and details of the loan will vary. It’s important to understand what type of financing your builder offers before choosing to finance through them.
Home equity loan
If you have an existing home with some equity built up, you can use a home equity loan to finance your tiny home build. Since home equity loans can be used for anything and are secured to your main home, you can typically get a low variable rate and lower loan payments than most other loan types. Just make sure you can afford the payments, since defaulting on a home equity loan means your lender can seize your home. Borrowing limits for home equity loans can also be limited based on your home’s value and remaining mortgage balance. Home equity financing can be a lump-sum loan, typically with a fixed rate, or a home equity line of credit (HELOC), which lets you borrow as needed up to a set limit, typically at a variable rate.
Traditional mortgage
While most lenders don’t offer tiny home traditional mortgages, some do. Paige Robinson, a real estate investor and the owner of House Buyers, said that getting a traditional mortgage on tiny homes depends on foundation and zoning. “Traditional mortgages require properties on permanent foundations,” she said. “Some jurisdictions allow tiny homes on permanent foundations, but it's essential to verify local regulations.”
Additionally, she said: “Tiny homes may not be permitted in all residential zones. Consult with local zoning authorities to ensure the property meets zoning requirements for mortgage eligibility.”
It’s also common to find loan products specifically designed for accessory dwelling units (ADUs). If you plan to rent out the ADU, some lenders may allow projected rental income to be considered when qualifying for the loan.
» COMPARE: Mortgage lenders
What determines eligibility for tiny home financing?
Once you've identified a tiny home financing option, you'll need to determine whether or not you qualify. Requirements vary by loan type and lender, but lenders generally consider:
Credit score and history: Minimum credit-score requirements vary by lender and loan type. Payment history and existing debts may also factor in.
Income and debt-to-income ratio: Lenders consider your income and existing debt payments to determine whether you can afford the new loan payment.
Down payment: Requirements vary by loan type, property and lender. A larger down payment generally means borrowing less and may improve your loan-to-value (LTV) ratio.
Tiny home eligibility as collateral: Not every tiny home qualifies as collateral. Lenders may have requirements related to the home's construction, mobility, location, foundation, title, or whether it's considered real or personal property.
Compare tiny home financing options
See how different loan options compare based on their pros and cons.
| Benefits | Drawbacks | |
|---|---|---|
| Personal loan | Fewer regulatory limits, multiple term lengths available | Higher interest rates, borrowing limits may restrict your budget |
| RV loan | Interest rates comparable with traditional mortgages | For RVs only, required vehicle approval by the RVIA |
| Builder financing | Direct financing option from home builder | Limited availability, terms may not be as competitive |
| Home equity loan | Multiple term lengths available, lower interest rates than personal loans | Requires high amount of equity in existing home, potentially higher interest rates than a traditional mortgage |
| Traditional mortgage | Typically longer financing terms, lower interest rates than personal loans | Local regulations may bar this option, best interest rates and terms reserved for high credit scores |
Pros and cons of tiny homes
Owning a tiny home can be financially advantageous and allow you to downsize, but there are some challenges with buying and living in a tiny home as well. Here are a few pros and cons of tiny homes to consider:
Pros
- Can be more affordable than a traditional home
- More eco friendly than a regular home
- May be cheaper to insure that a regular home
- Gives you mobility and flexibility in your home location
Cons
- Most don’t qualify for a traditional mortgage
- May not be able to build a tiny home in your municipality
- Can be expensive to buy land and run utilities to your tiny home
- Usually depreciate in value
FAQ
Can you finance a tiny home with a mortgage lender?
Financing a tiny home through a typical mortgage lender can be challenging. Some mortgage lenders might offer financing for manufactured homes or mobile homes, which might cover some tiny home types.
What credit score do I need for tiny house financing?
To qualify for tiny house financing, lenders typically look for a credit score of at least 600 to 620 as a minimum. However, the higher your credit score, the better your rates and loan options will be. Borrowers with excellent credit scores (720 and above) often receive the most favorable terms and interest rates.
How long are tiny house loan terms?
The length of tiny house loan terms can vary depending on the type of loan. Personal loans, which can be used for tiny homes, typically have shorter terms ranging from two to seven years. RV loans, on the other hand, can offer longer terms if the tiny house qualifies as a recreational vehicle; these loans can extend up to 10 to 15 years, providing lower monthly payments but potentially higher total interest over the life of the loan.
Bottom line
Financing a tiny home will be more affordable than purchasing a traditional home, but you will not have the same number of mortgage lender financing options available. For many, to make your tiny home financially possible, you will need to rely on savings and a strong credit score to obtain a favorable personal loan or RV loan.
Article sources
ConsumerAffairs writers primarily rely on government data, industry experts and original research from other reputable publications to inform their work. Specific sources for this article include:
National Association of Realtors, “Small House Movement.” Accessed Oct. 7, 2026.
Realtor.com, “Can I Put a Tiny House on My Property?' What to Know So You Don’t Break the Law.” Accessed Oct. 7, 2026.
RV Industry Association, “RV and Park Model RV Handbooks.” Accessed Oct. 7, 2026.
National Highway Traffic Safety Administration, “As a Federal agency, NHTSA regulates the safety of motor vehicles and related equipment.” Accessed Oct. 7, 2026.
HomeGuide, “How much does a tiny house cost?” Accessed Oct. 7, 2026.