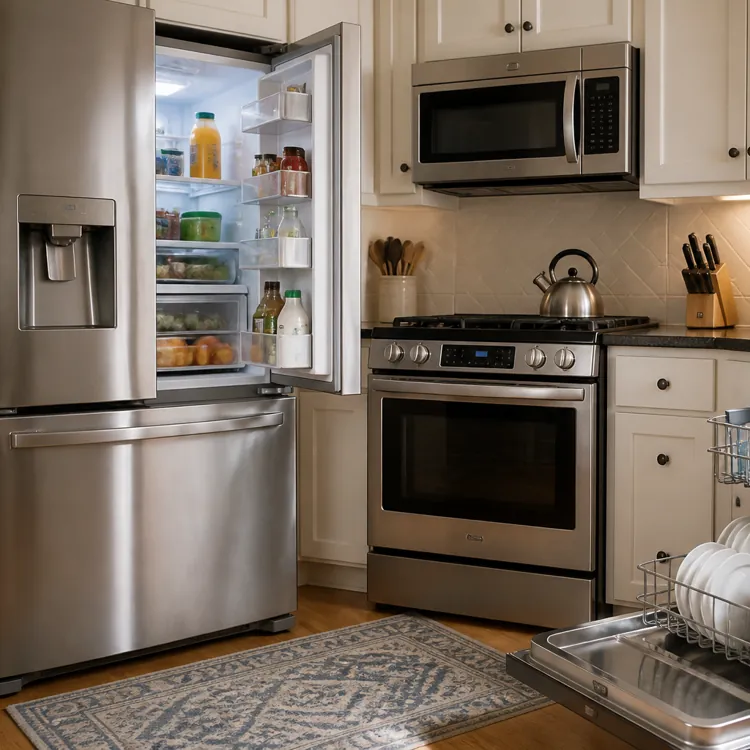
What is a home warranty?
A home warranty contract covers the repair and replacement costs of certain appliances and home systems that eventually fail due to regular, everyday use. With a home warranty, you pay an annual premium for the plan, plus a smaller per-claim service fee (also called a deductible) any time you need a service technician to come to your home.
Coverage varies based on the provider and plan, but most standard plans include big-ticket items such as:
Systems:
Electrical
Plumbing
Heating and air conditioning (HVAC)
Appliances:
Oven
Stove
Dishwasher
Refrigerator
Washing machine
Dryer
Built-in microwave
Home warranty vs. homeowners insurance
There are a few key differences between home warranties and homeowners insurance. Homeowners insurance provides coverage to the home's structure if there's ever unexpected damage or loss due to events such as theft, wind or fire. Home warranties address the inevitable breakdown of appliances and systems within the home—nothing structural.
Homeowners insurance is required by most lenders until the loan is paid off, while home warranties are typically optional.
Who purchases a home warranty plan?
Home warranties can be purchased by new homeowners or by sellers as an additional incentive for prospective buyers. Sellers often opt for a one-year warranty to protect against unexpected costs during the closing process, providing peace of mind for both parties. A home warranty can also provide the seller with protection during the listing and escrow period.
“It is a requirement that our buyers have a home warranty for our closings,” explained Sam Olson of The Olson Group, a real estate agency in Reno, Nevada. “Typically, we will ask the seller to purchase one for the buyer, but in tighter negotiations, the cost often falls on the buyer’s agent to provide a home warranty.”
If you’re a new homebuyer, purchasing a home warranty plan can provide peace of mind as you become familiar with your property and learn more about the condition of its appliances and systems. Additionally, if you’d rather avoid the hassle of finding and vetting technicians and contractors in your area, your home warranty provider will handle this for you by assigning a trusted, approved technician if service is needed.
» LEARN MORE: Is a home warranty worth it?

How do home warranties work?
After enrolling in a home warranty, most providers will require a waiting period before you can begin filing claims. The standard waiting period for home warranties is 30 days, although this can vary by provider.
Once the waiting period ends, you can file a claim with your home warranty provider if a major appliance or system stops working. Not all home warranty plans and companies are exactly alike, but the general process is the same. The steps include:
Confirm coverage: Review your contract to ensure the item or system is covered. You can always contact your provider if you are unsure.
Contact the provider: Use your home warranty company’s designated method to ensure a smooth filing process. This is often by phone, through an online portal or a mobile app.
File your claim: Follow the prompts for submitting your claim, including details about the broken item. This may include age, brand, model and serial number, with a description of the issues.
Pay the service fee: Once you file the claim, you will need to pay the deductible, also known as a service call fee. The cost of your service fee should be clearly listed in your contract.
Schedule service: The home warranty company will then assign an authorized contractor or technician to your case, who will contact you to schedule a service visit at a time that works best for you.
Approval for repairs: During the visit, your technician will review and diagnose the issue. The warranty company will confirm whether it’s covered and then give final approval so the technician can proceed with the necessary repairs or a replacement.
Keep records: It’s important to document all communication with your home warranty provider and assigned technicians. This may help you if any issues arise during the servicing or payment processes.
It’s also recommended to keep documentation of the maintenance history of your broken system or item to receive approval for repairs and replacement from your home warranty provider.
Service fees and payment process
The service call fee, also called a deductible, is a specified amount outlined in your home warranty contract that you must pay each time you file a claim or a technician visits your home. Service fees vary, but most companies charge between $75 and $150. Some home warranty companies charge a flat rate, while others offer a range depending on the policy.
Some home warranty providers charge a service fee each time a technician visits your home for repairs. Others offer a repair guarantee, meaning you won’t be charged additional service fees if the contractor has to return multiple times within a specified timeframe to complete a job. Be sure to thoroughly review the terms and conditions of your home warranty plan so that you know what to expect.
Renewal, cancellation and transferability
A home warranty contract will outline details about the term, including what happens when coverage expires. Most home warranty contracts last 12 months. Coverage will end on the date specified in your contract, after which you will not be able to file claims or receive covered services.
Your provider may contact you with a renewal notice when your plan's expiration date is near. If you'd like to renew, you can follow the steps outlined by your provider to avoid any lapses in coverage. Be sure to verify that the renewal is actually from your provider and avoid any potential home warranty scams.
If you sign up for a home warranty and change your mind, you may be able to cancel and receive a refund. Some providers allow cancellations within a certain window of time after the effective start date.
Finally, most home warranty plans are transferable if you sell your home during the contract term. Your home warranty contract should note the details about transferring coverage to a new homeowner.
What does a home warranty cover?
The coverage included in your home warranty contract depends on the plan you select. Most home warranty providers offer systems-only plans, appliances-only plans and a combination of both.
Coverage can also vary by location and will likely include specific limitations, exclusions and coverage caps. For this reason, it’s important to carefully review each provider’s terms and conditions to find the plan that best suits your needs.
System plans
The primary home systems covered under standard warranty plans are HVAC, plumbing and electrical, with some plans also covering water heaters, ductwork and ceiling fans.
HVAC: Plans typically include repairs or replacements for mechanical components such as thermostats, motors, compressors, condensers, pumps, fans and coils, as well as associated electrical components.
Plumbing: Plans may cover repair service for leaks, ruptures, bursts or blockages, as well as malfunctioning valves, faucets, showerheads, pumps, motors and switches.
Electrical: Plans commonly cover the hard-wired components of electrical systems, such as interior wiring, outlets, switches or breakers.
It’s important to note that a standard home warranty plan may not (and likely does not) cover all components of or issues related to these systems. Be sure to review the limitations and exclusions detailed in your contract.
Appliance plans
Appliance plans cover major household appliances, such as refrigerators, stoves, ovens and dishwashers. However, coverage can differ depending on the provider and plan. Most standard plans also include built-in microwaves, washing machines and dryers, while others require a more comprehensive plan or additional coverage for these items.
If you have other appliances, such as a wine cooler or freezer, or high-end items like a professional-grade oven or custom-built appliance, you may need to opt for an upgraded plan due to higher potential repair costs.
Combo plans
A combination home warranty plan offers coverage for both home systems and appliances. These plans typically cost more than systems-only or appliance-only options, but the added coverage might be worth it depending on the age and condition of your home and its appliances.
Standard combination plans typically cover essential home systems like HVAC, electrical and plumbing, along with major appliances such as refrigerators, ovens, stoves and dishwashers. More expensive plans may extend coverage to items such as ceiling or attic fans, doorbells, garbage disposals, trash compactors or garage door openers. Many home warranty providers also offer optional add-on coverage for a broader range of items for an extra fee.
Which type of home warranty plan should you get?
To choose the right coverage plan for you, consider the state and age of your home, as well as the appliances you have. An aging home is likely to have systems and appliances that will need more frequent servicing. In this case, a combination plan may make more sense.
If you’re a first-time homebuyer, purchasing a combination plan may help you manage unexpected costs as you become familiar with your property and its systems.
If your appliances are newer and covered by the manufacturer's warranty, you may not need a plan that includes appliance coverage. In that case, you may consider opting for a systems-only plan.
Assess the condition of your home and appliances, then compare the costs and coverage limits offered by the home warranty company.
» FIND OUT: When can you buy a home warranty?
Home warranty exclusions and limitations
Home warranty plans cover issues arising from the regular use of your everyday appliances and systems — not unexpected structural damage or loss due to fire or theft, which are covered by homeowners insurance. Home warranties do not cover preexisting or structural issues or problems caused by improper maintenance or misuse of your appliances or systems.
“Home warranty plans do not cover everything, and often not the ancillary costs of repairs. For instance, if a shower cartridge repair is covered, the repair to the drywall to access the shower to complete the repair is not,” Olson said.
Preexisting conditions
Home warranty providers typically will not cover preexisting conditions or issues known before the warranty began. They only cover breakdowns caused by wear and tear that occur after your plan starts.
“A home warranty will not cover something that was broken when the home closed. It must be working, and then not working, for a warranty to cover it,” explained Olson.
These conditions are categorized by:
Known preexisting conditions: Detected or disclosed before the warranty began
Unknown preexisting conditions: Hidden issues that were not identified beforehand
Some home warranty companies require an inspection before beginning your coverage plan. If an issue was not detected during inspection, your provider may offer coverage for this unknown preexisting condition. However, each provider has different policies. Carefully review your contract and keep maintenance records on hand to help prevent potential claim denials.
Structural issues
Structural components that are not covered by home warranties include issues with your home's foundation, walls, windows or roof. Additionally, “a home warranty generally doesn’t cover anything outside of the home’s footprint,” said Olson. “Sprinkler systems are not covered, and sewer line stoppages are not covered if they happen between the house and the sewer main.”
Improper use or maintenance
Damage or defects resulting from improper use or maintenance of your appliances or systems are not covered by home warranty providers. Additionally, many home warranty plans do not cover appliances or systems installed incorrectly. This includes problems arising from a system or appliance that violates building codes.
Other common exclusions include:
Additional appliances, such as a second refrigerator
Pools, spas or outdoor kitchens
Certain components of plumbing and electrical systems, such as water filtration
Coverage limitations
A coverage limit is the maximum amount your home warranty provider will pay for a claim or coverage category. It’s important to understand the limits outlined in your policy to make decisions and manage expectations for both parties. Keep in mind that basic coverage plans will have lower coverage limits than more comprehensive plans, and once you’ve reached your maximum coverage limit for an item or system, you may have to pay out of pocket.
Types of coverage limits include per-item, per-occurrence and aggregate limits.
Per-item limits: The maximum payout for a single item or system that the provider will pay. If the cost to repair or replace your refrigerator is $2,500 and your per-item coverage limit is $2,000, you will be responsible for the $500 difference.
Per-occurrence limits: These specify the maximum amount your home warranty provider will pay for each individual claim or service call.
Aggregate limits: The maximum the provider will pay over the course of your entire policy term (regardless of the number of claims made).
Luxury and older appliances often exceed standard home warranty limits as they cost more to service and replace. High-end appliances with smart technology may require specialized technicians or proprietary parts, which can drive up service costs.
In addition, some providers will limit the number of service calls allowed during the contract term.
Choosing a home warranty company
There are a handful of factors to consider when choosing the right home warranty company for you, including plan types, pricing, coverage limits and customer service.
Plan types
Determine which type of home warranty plan you need. Are you looking for coverage for systems and appliances, or just one or the other? Make a list of all the appliances and systems in your home, along with their ages and current conditions.
If you have outdated appliances but newer plumbing or HVAC systems, you may consider opting for an appliance-only plan. If everything in your home is aging and may soon need servicing, or you’re a new homebuyer and aren't entirely sure of the conditions, you may consider a combination plan that offers more coverage.
You’ll also want to consider which major appliances are included in the plans. Do you have a clothes washer and dryer that need coverage? Do you have a luxury refrigerator or oven with smart technology? If so, make sure the plan you’re considering includes those, with coverage limits that make sense for your appliances.
Pricing and premiums
Determining what your monthly budget is can help you narrow down your plan options. Premium prices and service fees vary by plan, which is why it’s important to get quotes from a few different home warranty companies to compare your options. Generally, the higher your deductible (or service call fee), the lower your monthly payment.
Home warranty plans typically cost between $350 and $900 each year, depending on factors such as your plan’s premium, service call fees, extended coverage and your location. Most home warranty contracts last 12 months, and you can choose to pay monthly or annually, with average monthly payments ranging from $30 to $90.
Coverage limits
Take another look at your list of appliances and systems, and consider the average cost to repair or replace them. Is your refrigerator old and on its way out? Does the HVAC system need servicing soon? Consider what the plan’s per-item coverage limit is and how much you may have to potentially pay out of pocket.
Customer service
Going through the home warranty process can be a headache—filing claims, scheduling and coordinating technicians, going without certain appliances or systems while waiting for servicing, payment processes, paperwork and potential claim denials. It’s important to consider whether you prefer working with a larger, online home warranty company or a local one.
“We always recommend a home warranty company with a local representative, who can often simplify the claim process. Large, internet-only providers often have fewer options, less support, and sometimes don’t even cover everything they say they do,” said Olson.
Be sure to read online reviews or ask trusted friends, family or neighbors for recommendations. Choosing a reputable home warranty company that partners with qualified, reliable technicians is key to ensuring a positive experience.
» CHECK OUT: Best home warranty companies of 2026
FAQ
What are the cons of a home warranty?
Home warranty plans include exclusions and limitations, meaning not everything related to your appliances or home systems may be covered. “The biggest downsides of a home warranty are the upfront cost and the consumer’s misunderstanding as to coverage,” said Olson.
A home warranty plan is worth it if the total costs are less than what you would have otherwise paid to fix or replace faulty equipment. You may get lucky and not need to use your home warranty plan—but if you do, you might consider the plan a waste of money.
Another potential downside is the additional time it may take to coordinate your services with the home warranty company and the technicians. Since everything has to be approved through your home warranty provider (rather than you hiring a contractor or technician yourself), the process may be delayed, which can be annoying if you’re going without an essential everyday appliance or system in the meantime.
What do home warranties typically cover?
A standard home warranty plan typically provides coverage for repairs and replacements of major household appliances and systems that break down due to everyday use. These appliances commonly include refrigerators, ovens, stoves, dishwashers, washing machines and dryers. The systems include HVAC, electrical and plumbing.
Home warranty plans do not include structural issues, preexisting conditions or damage or loss caused by unexpected events such as fire or theft.
How often do you pay for a home warranty?
Home warranties can be paid either as an upfront annual premium or in monthly installments, depending on the provider and your plan. In addition to these payments, a separate service fee is charged each time you make a claim or a service technician visits your home. Most plans have a one-year term, though some companies offer longer durations.
Is a home warranty required?
Home warranties are optional. They are not legally required by state or federal law in the U.S. However, regulations may vary depending on the situation — for example, some states require home builders to provide a one-year warranty. Certain real estate agencies may require proof of a home warranty before closing on a property.
What should I do if my home warranty claim is denied?
You can begin by contacting your provider and requesting a detailed explanation about why the claim was denied. If you disagree with the decision, gather any supporting documentation you have (including maintenance records, inspection reports, photos and communication with the provider). From there, you can begin the provider's process to formally appeal the decision.
Article sources
ConsumerAffairs writers primarily rely on government data, industry experts and original research from other reputable publications to inform their work. Specific sources for this article include:
Home Warranty of America, “Take the Worry Out of Home Ownership With a Home Warranty.” Accessed Sept. 16, 2026.
The Hartford, “Home Warranty vs. Home Insurance.” Accessed Sept. 16, 2026.
First American Home Warranty, “How the Home Warranty Service Process Works.” Accessed Sept. 16, 2026.
Liberty Homeguard, “Home Warranty Deductible: What to Know Before You Buy Your Home Warranty.” Accessed Sept. 16, 2026.
Liberty Homeguard, “Does a Home Warranty Cover Plumbing Systems?” Accessed Sept. 16, 2026.
Liberty Homeguard, “Does a Home Warranty Cover Appliances?” Accessed Sept. 16, 2026.
Modernize, “How to Evaluate a Home Warranty Policy.” Accessed Sept. 16, 2026.
Modernize, “Do Home Warranties Cover Pre-Existing Conditions?” Accessed Sept. 16, 2026.
HSH Advisor, “What Does a Home Warranty Cover?” Accessed Sept. 16, 2026.
Liberty Homeguard, “Coverage Limit.” Accessed Sept. 16, 2026.
Liberty Homeguard, "When Home Warranties Expire and Cease to Function." Accessed Sept. 16, 2026.
Cinch Home Services, “Is Home Warranty Coverage Required in the US in 2024?” Accessed Sept. 16, 2026.