Key insights
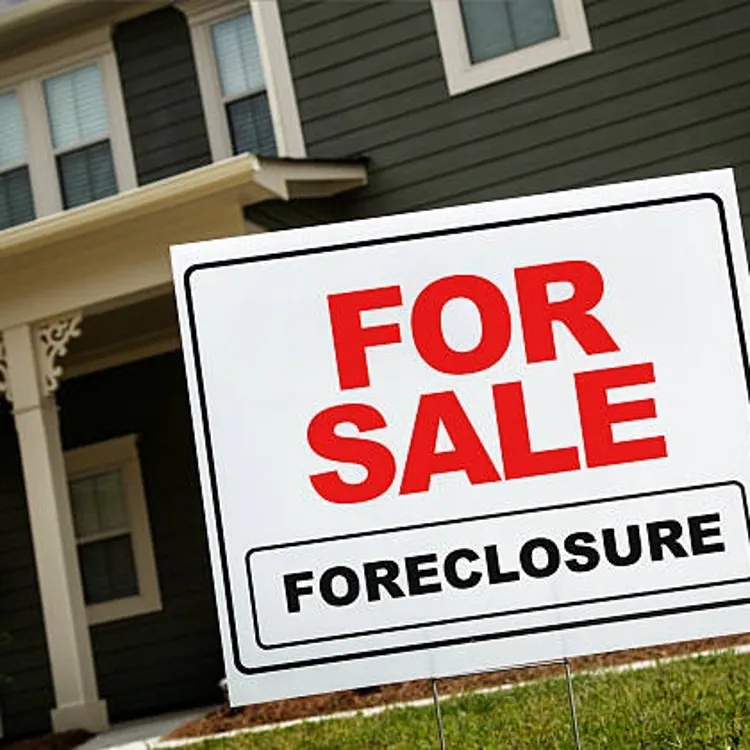
If a homeowner defaults on their mortgage and the home doesn’t sell at a foreclosure auction, it becomes a bank-owned property.
Jump to insightMost bank-owned homes are sold as-is, so an inspection and a realistic repair fund are central to deciding whether the deal is worth it.
Jump to insightBuying a bank-owned property may take much longer than buying a standard property.
Jump to insightWhat is a bank-owned property?
A bank-owned or real estate owned (REO) property is a property that a bank, lender or loan servicer owns after a foreclosure-related event.
When a homeowner defaults on their mortgage, the lender may offer the home at a foreclosure auction. The goal is to sell it to the highest bidder so the lender can recoup as much of the outstanding loan as possible. If the property fails to sell at auction, ownership reverts to the mortgage lender or loan servicer, and it becomes bank-owned.
Buying a bank-owned home is different from a foreclosure auction purchase. With an REO property, the lender has already taken ownership and typically lists the home through a real estate agent. The process varies, but it usually gives buyers more opportunity to view the property, arrange financing and conduct due diligence than they would have at an auction.
Pros of buying a bank-owned property
Purchasing a bank-owned property is a very different process than purchasing a traditional home. However, a bank-owned home can create a great opening for a prepared buyer.
1. Potentially more competitive price
Banks aren't in the business of property management, and buying a bank-owned property may mean getting a bargain on a home that's priced to sell. Not every REO home sells below fair market value, but you'll have a better chance to build equity and earn a higher return on your investment if you can buy at a discount.
The purchase price isn’t the only potential saving. Some bank-owned properties come with a low down payment or a discounted interest rate. Plus, you may be able to negotiate closing costs with the bank for further savings.
2. Greater investment potential
If you buy a property at a substantial discount, you have more options to maximize your return. You can fix it up yourself and flip it for a profit. You might also keep it and rent it out for monthly income, or live in it while enjoying the benefits of a lower home price.
3. Less competition against other buyers
The drawn-out process of buying a bank-owned property doesn’t appeal to every buyer because of the longer purchase timeline and the higher risk of needed remodeling and repairs, among other factors. Investors may also show less interest as they focus on other property types for their portfolios. Both these scenarios mean less competition for you as a buyer.
4. Lower chance of title issues
Banks and loan servicers generally work to clear title problems before listing an REO home. That means reduced risk of dealing with certain liens or ownership disputes later on.
Still, this advantage comes with a caveat: You may receive a clear title through a special warranty deed, which covers title only while the bank owned the property.
Désirée Ávila, a real estate agent with Charles Rutenberg Realty in Fort Lauderdale, Florida, warned: “This does not guarantee the buyer against any future claims to the title beyond when the bank owned it. A buyer should talk to an attorney and understand what the ramifications, if any, there could be if they take title as a special warranty deed or other type of deed.”
» MORE: What is title insurance?
Cons of buying a bank-owned property
Potential savings and reduced competition among buyers might sway you toward buying a bank-owned property, but anyone considering one should know the drawbacks upfront.
1. Possible repairs needed
A financial institution may address some cosmetic and/or structural issues once it takes possession, but there’s no guarantee it will fix every problem, and most sell as-is. You can conduct a home inspection with these transactions and find out more about repairs upfront. However, the bank isn’t likely to offer any repair concessions. Anyone purchasing this type of distressed property should understand that it may need extensive repairs.
“The price appears to be the most obvious advantage [when purchasing a bank-owned property]. If there is nothing wrong with the house, then it probably is. However, if there are a lot of things wrong with the house, what seemed like an advantage could feel to a buyer like fool's gold,” Ávila explained.
If there are a lot of things wrong with the house, what seemed like an advantage could feel to a buyer like fool's gold."
2. Limited finance options
You can pay cash for a bank-owned property or finance it with a mortgage, but you may find your REI financing options are more limited than they would be if you were purchasing a traditional property. For example, lenders may require extra documentation, and some properties might not qualify for certain programs until repairs are completed. If the property has severe structural damage, don’t expect traditional mortgage lenders to approve the application.
3. Longer purchase process
You might assume that dealing directly with a financial institution that owns the property will make the purchase process easier, but in reality, these transactions typically take longer. Multiple parties get involved in each part of the closing, such as submitting and approving an offer, which further delays the sale.
In this case, a buyer who wants to move the sale forward is working with a financial institution that wants to avoid another future foreclosure. That means the institution will scrutinize every aspect of the transaction.
» MORE: How to finance home renovations
How to buy a bank-owned property
Purchasing a bank-owned home requires careful planning and an understanding of the process. Here’s what it looks like:
Find REO listings: Search bank websites, foreclosure databases and real estate listing sites for available REO properties. Consider working with a real estate agent experienced in these transactions.
Secure appropriate financing: Explore your financing options early, whether paying in cash or using a mortgage product that works for REO properties.
Conduct thorough due diligence: Arrange for an independent home inspection as soon as the contract permits, and preserve an inspection contingency when possible. Then, conduct a title search and review all public records to fully understand the property’s condition and history.
Navigate the negotiation process: Submit your offer to the bank and be prepared for possible counteroffers or delays due to the institution’s approval procedures.
Complete the closing process: Once your offer is accepted, finalize financing, sign all necessary paperwork and ensure all legal requirements are met before taking ownership.
Should you buy a bank-owned home?
Buying a bank-owned property isn’t the fastest path to homeownership, but you can buy it at a reduced price or save on closing costs. As you consider buying a bank-owned property, ask yourself the following questions:
Am I comfortable with a longer purchase timeline?
Do I have additional money for repairs, some of which are likely to be extensive and costly?
Is the financing that I qualify for available for this type of property?
Will I conduct a title search and home inspection and add any contingencies to the offer if necessary?
Is this an investment property or a primary residence?
If you do pursue a bank-owned property, it’s best to work with a real estate agent experienced with the buying process who can show you comparable properties in the area and guide you through the sale.
FAQ
Where can I find bank-owned properties for sale?
You can find bank-owned properties for sale on websites dedicated to these properties. Some banks, such as Bank of America and Wells Fargo, list the available properties directly on their websites. Other banks and credit unions redirect you to a real estate office. You can search independent foreclosure databases, too, such as RealtyTrac and HUDHomesUSA.
Do I need a real estate agent to buy a bank-owned property?
You’re not required to use a real estate agent to purchase a bank-owned property. However, an experienced agent can offer valuable advice and support throughout the process. You can ask for an agent experienced with REO properties and the extra paperwork involved.
Can I negotiate the price of a bank-owned property?
Yes, you can offer a purchase price over or under the listing price, although not all financial institutions will negotiate. Remember, not only is the purchase price negotiable, but so are other costs, such as closing costs, the interest rate and the down payment amount.
Are bank-owned homes good for first-time buyers?
They can be, but it depends on the buyer’s situation. First-time buyers who are flexible with their move-in timeline, have funds for potential repairs and are willing to navigate a more complex purchase process might find a great deal. However, those seeking a quick, move-in-ready home may find the challenges outweigh the benefits.
Bottom line
Finding a bank-owned property is a potential way to save money on a home purchase, as the property may have a low price, interest rate or down payment requirement. But the path to purchase is often long and bumpy and deserves careful consideration.
If this still interests you, start by checking out available properties and enlisting the help of a real estate agent specializing in REO properties. The more you understand the process and dealings with the lending institution, the better your chances of success in completing the purchase.
Article sources
ConsumerAffairs writers primarily rely on government data, industry experts and original research from other reputable publications to inform their work. Specific sources for this article include:
Consumer Financial Protection Bureau, “How Does Foreclosure Work?” Accessed Oct. 1, 2026.
Consumer Financial Protection Bureau, “Find the Right Home.” Accessed Oct. 1, 2026.
Bank of America, “Search REO and Bank Owned Homes.” Accessed Oct. 1, 2026.
RealtyTrac, “RealtyTrac.” Accessed Oct. 1, 2026.