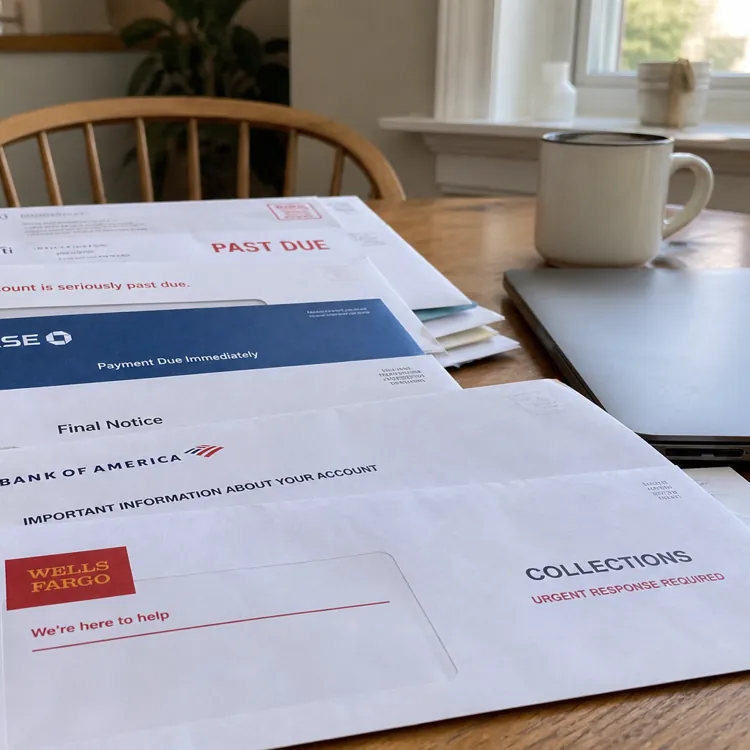
The life cycle of a missed credit card payment
Your credit card issuer requires that you make at least the minimum payment shown on your monthly statement by the payment due date. This date can fall on any date of the month, depending on your card issuer and when you originally applied, but generally falls on the same calendar day each month.
Separately, your card issuer also has a reporting date, often called a statement closing date. This is when it reports your account information to at least one of the three credit bureaus each billing cycle.
If you pay even a day or two late, you may get hit with a late fee. The fee amount depends on the issuer, the account terms and applicable law. Federal Regulation Z sets safe-harbor limits for many late fees, but issuers can impose lower fees and cannot generally charge more than the required minimum payment that was due.
According to John Ulzheimer, president of The Ulzheimer Group and founder of CreditExpertWitness.com, the life cycle of a missed credit card payment can be broken down like this:
You're 30 days late
Credit reporting standards don’t allow card issuers to report a late payment to the credit bureaus until at least 30 days have passed without a payment since your due date.
"So, while you are certainly late even if you're one day past the due date, you'll have to go a full 30 days before the record of the late payment ends up on your credit reports," Ulzheimer said.
He added that you can make a payment at this point, which will put you back to the "current" status. From there, the late payment record will begin to age, becoming a historical late payment rather than a current one.
You're 60 days late
Once you're at least 60 days late on your credit card payment, the card issuer can report it immediately on its regular reporting date within a billing cycle. The same is true when you're 90, 120, 150 or 180 days late on your credit card bill.
This milestone can also affect your interest rate. Under federal credit card rules, an issuer generally may increase the annual percentage rate (APR) on existing balances due to a late payment only after it has not received the required minimum payment within 60 days after the due date. The issuer must provide notice before the increase takes effect.
Note that the card issuers can charge you a late fee for each credit card bill you miss, and these fees keep adding to your balance along with the interest that accrues.
You're 180 days late
Ulzheimer said that once your credit card bill is more than 180 days late, credit card issuers will stop reporting late payments on your account: "At this point, it's likely the card issuer has closed the account to new charges and perhaps has even written off the account as a loss.” This is a charge-off and doesn’t erase your obligation to pay.
Since you can no longer get back on track with payments and your debt has almost certainly moved into the hands of a collection agency, you’ll be left to deal with debt collectors, or you can pay off or settle the account.
You have the right to ask debt collectors to stop calling you, along with other rights under the Fair Debt Collection Practices Act (FDCPA). However, these rights don't prevent debt collectors from suing you for unpaid debt amounts or reporting the collection activity to the credit bureaus.
While even a single missed or late credit card payment can impact your credit score, the consequences become more severe as 30 to 60 days and 90 to 180 days pass after your bill was originally due.
To illustrate, a simulation on the FICO website shows that a consumer with a starting score of 793 could see it drop by 63 to 83 points after missing a payment by 30 days. They may see a drop of 113 to 133 points from the starting score after a 90-day missed payment period.
Most negative account information, including late payments and collections, can generally remain on a credit report for up to seven years.
» COMPARE: Best credit report sites
What happens to promotional offers if you miss a payment?
A missed payment can put a promotional APR or introductory offer at risk, but the timing matters. Federal rules generally prohibit an issuer from increasing or revoking an introductory rate before it ends unless the required minimum payment is more than 60 days late.
When that happens, your balance may shift to the card’s regular APR or a higher penalty APR. The issuer must generally disclose the potential penalty rate and the circumstances that can trigger it in your account opening disclosures and periodic statements, so read them carefully to know what to expect.
If payments stay overdue, here’s what else can change:
- Interest charges may rise as the balance remains unpaid.
- The issuer may close the account to new purchases.
- Continued nonpayment may lead to a charge-off and collections.
Acting early, even after one missed payment, can help limit damage by preserving your promotional terms or arranging temporary relief. The earlier you contact the card issuer, the more options you'll have. Those options vary by issuer and are not guaranteed.
How credit card issuers and collectors contact you
Credit card companies and debt collectors follow a fairly predictable communication path when you miss a payment. Specifics vary by issuer, but knowing what to expect at each stage can help you respond early and protect your rights.
1. Payment reminders and late notices
After a missed due date, issuers usually start with friendly reminders by email, text or app notification. If the payment remains unpaid, you’ll receive a formal late notice by mail or email explaining the past-due amount, any late fees and the risk of a higher APR or account restrictions.
2. Escalation calls and warning letters
If the balance stays overdue, expect more frequent phone calls and written warnings. The issuer may warn that it could close the account, report a delinquency, increase the APR where legally permitted or charge off the balance.
Don’t assume a phone conversation changes your payment obligations. Ask for any hardship plan, settlement offer or payment arrangement in writing before relying on it.
3. Charge-off notice
After about 180 days of nonpayment, the issuer may charge off the account. You’ll receive a notice stating the account has been closed and written off as a loss. You still owe the balance, and the charge-off will be reported to the credit bureaus. The issuer may continue collecting, assign the account to a collection agency or sell it to a debt buyer.
4. Collections communications
Once the debt is sent or sold to a collector, you may get letters or calls requesting payment. Under federal law, collectors must identify themselves, provide written validation of the debt, and avoid abusive or misleading tactics.
Your rights and next steps
Federal debt collection law gives consumers important protections, but it does not make a valid debt disappear or prevent a collector from filing a lawsuit.
Through a written request, you can:
- Request written proof of the debt.
- Dispute an inaccurate balance or a debt that is not yours.
- Limit when and how collectors contact you.
If you receive a legal notice, court summons or demand letter, do not ignore it. Read it carefully, respond by the stated deadline, and consider speaking with a consumer law attorney or legal aid organization in your state. Keep copies of all communications to protect yourself.
Legal consequences of unpaid credit card debt
When credit card debt remains unpaid, it can escalate from calls and letters to formal legal action. Understanding the possible consequences can help you act before the situation becomes harder and more expensive to fix.
Lawsuits
A creditor or debt collector may file a lawsuit to recover the unpaid balance. You should receive a summons and complaint identifying the party suing you, the amount claimed and the court deadline for responding. If you ignore it, the court may issue a default judgment against you, even if the amount is incorrect or the debt is not yours.
Judgments
If the creditor wins the case or you fail to respond, the court can enter a judgment. This gives the creditor legal authority to pursue stronger collection tools. State law largely governs judgments, and they can accrue interest. The time a judgment remains enforceable, whether it can be renewed and the available collection methods differ by state.
Wage garnishment
For most consumer credit card debts, a creditor generally needs a court judgment before it can garnish your wages. Federal law limits how much can be garnished, and some states offer stronger protections or exemptions.
Bank levies
A bank levy allows a creditor to freeze and seize money from your bank account. This can leave you temporarily unable to access funds for rent, food or bills. Some types of income, such as Social Security benefits, may be protected, but you often have to assert those exemptions.
Property liens
In certain cases, a creditor can place a lien on your home or other property. A lien doesn’t always mean immediate seizure, but it can block a sale or refinance until you resolve the debt.
Know your rights and act early
Debt collection laws, statutes of limitations and creditor remedies vary by state. You have the right to be notified of lawsuits, to contest the debt, and to claim exemptions that protect part of your income or assets. If you receive legal papers, respond by the stated deadline. Early action can sometimes lead to settlements or payment plans that prevent harsher outcomes.
What to do if you can’t pay your credit card bill
Ulzheimer said consumers who can’t make the minimum payment on their credit card bills have some choices, but that "none of them are great."
Here are a few steps to consider if you find yourself in this situation:
- Negotiate with the creditor. In the early stages of a late credit card bill, you may be able to pay the card issuer to get "current" on the debt. The Federal Trade Commission (FTC) says reaching out to your card issuer is a good way to start the conversation. You may be able to work on a modified payment plan with the card issuer. Contacting the issuer before the account becomes 30 days late can preserve more options.
- Look into debt settlement. Once a debt is with a collection agency, you may be able to settle it for the amount owed or less. You may be able to settle unpaid bills on your own, but you can also get help from a debt settlement company.
- Work with a nonprofit credit counselor. Individuals drowning in credit card bills can consider working with a credit counseling agency, particularly one that is a member of the National Foundation for Credit Counseling (NFCC).
- Sign up for a debt management plan. Some third-party companies help consumers who are late on bills get on a debt management plan (DMP). With a DMP, you make a single monthly payment to the debt solutions company. It manages and pays credit card debts and other bills on your behalf while negotiating lower interest rates and waived fees.
- File for bankruptcy. Finally, Ulzheimer says consumers who can’t pay their bills can always seek bankruptcy protection. That said, filing for bankruptcy has notable downsides, as it can ruin your credit and remain on your credit reports for up to 10 years, depending on the type of bankruptcy.
» MORE: Should you get a personal loan to pay off credit card debt?
FAQ
When is a credit card payment late?
A credit card payment is considered late when you’re even one day past your due date. However, card issuers can’t report late payments to the credit bureaus until at least 30 days have passed since the payment due date.
» COMPARE: Credit freeze vs. credit lock
What is a delinquent account?
Credit card account delinquency occurs when you're at least 30 days late making a payment.
How long does a missed credit card payment stay on record?
Late credit card payments and other negative information stay on your credit reports for seven years. After that, the information can still be in your credit file even if it’s no longer actively listed on your reports.
» MORE: What is a bank levy?
What is the statute of limitations on debt?
Some states set a statute of limitations on debt collection, or how long collection agencies and other creditors can legally pursue an unpaid debt. These limitations are usually between three and six years, but they can be longer or vary based on the type of debt or the state law in your credit agreement.
Make sure you understand the debt collection laws in your state and know which debts you’re truly responsible for. For instance, if a spouse or parent passes away, creditors may not be able to hold you liable.
» MORE: How is debt divided in divorce?
Bottom line
It’s always smart to pay your credit card on time, but sometimes life happens and keeping up with bills can be a challenge. Missing a credit card payment doesn’t automatically create a long-term credit crisis, but delaying action can make the debt more expensive and harder to resolve.
Paying at least the minimum due by the due date generally keeps the account current. If that’s not possible for you, contact the issuer immediately, keep written records of any arrangement and review your credit reports for accuracy.
A late payment can lead to escalating fees, interest, negative credit reporting, collections and, in some cases, a lawsuit. That said, you have rights under the FDCPA, including the right to tell debt collectors to stop contacting you and to dispute a debt you don’t recognize. If you get legal papers, respond on time and don’t assume the problem will go away.
Article sources
ConsumerAffairs writers primarily rely on government data, industry experts and original research from other reputable publications to inform their work. Specific sources for this article include:
- FTC Consumer Advice, “Debt Collection FAQs.” Accessed Sept. 6, 2026.
- Experian, “Can One 30-Day Late Payment Hurt Your Credit?” Accessed Sept. 6, 2026.
- FICO, “What’s in my FICO Scores?” Accessed Sept. 6, 2026.
- VantageScore, “The Complete Guide to Your VantageScore.” Accessed Sept. 6, 2026.
- Federal Register, “Credit Card Penalty Fees (Regulation Z).” Accessed Sept. 6, 2026.
- Consumer Financial Protection Bureau, “How Long Does Negative Information Remain On My Credit Report?” Accessed Sept. 6, 2026.
- Consumer Financial Protection Bureau, “What Is a Debt Collector and Why Are They Contacting Me?” Accessed Sept. 6, 2026.
- FICO, “How Credit Actions Impact FICO Scores.” Accessed Sept. 6, 2026.
- Federal Trade Commission, “How to Get Out of Debt.” Accessed Sept. 6, 2026.
- Discover, “What Happens When My Credit Card Goes Delinquent?” Accessed Sept. 6, 2026.
- Consumer Financial Protection Bureau, “Can Debt Collectors Collect A Debt That’s Several Years Old?” Accessed Sept. 6, 2026.
- Equifax, “What is a Charge-Off?” Accessed Sept. 6, 2026.