Key insights
It’s difficult to qualify for IRS tax forgiveness, and you may have to pay additional fees and penalties.
Jump to insightThe IRS provides several options for tax forgiveness, including a payment plan, an offer in compromise and spousal relief.
Jump to insightYou can apply for a payment plan or an offer in compromise through an online IRS account.
Jump to insightWho is eligible for tax forgiveness?
Eligibility for tax forgiveness depends on the specific program, but the IRS generally looks at your ability to pay, financial hardship and compliance with tax requirements.
You may be eligible for tax forgiveness if you:
Have filed all required tax returns
Can’t afford to pay your full tax debt without financial hardship
Have limited income, assets or both
Can demonstrate your financial situation with documentation
Are not currently in an open bankruptcy proceeding (for some programs)
You may not be eligible for tax forgiveness if you:
Have unfiled tax returns
Have the ability to pay your debt in full or through a payment plan
Provide incomplete or inaccurate financial information
Fail to stay current on required tax filings and payments
Are attempting to qualify without meeting basic IRS compliance requirements
IRS tax forgiveness programs
The IRS offers several tax forgiveness programs to help you if you’re unable to pay your tax debt in full.
| Program | What it does | Who it’s best for | Drawbacks | How to apply |
|---|---|---|---|---|
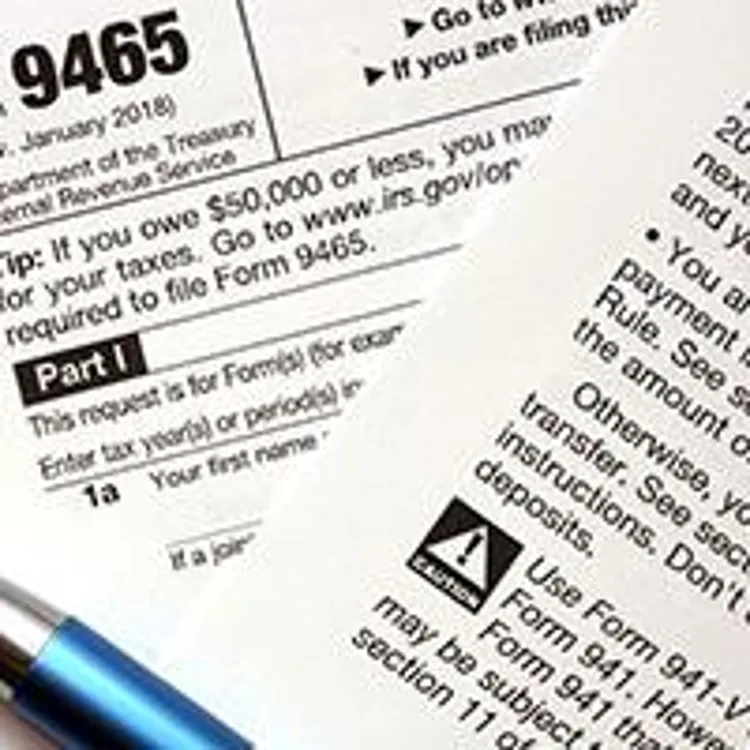
| Payment plan (installment agreement) | Lets you pay your tax debt over time in monthly payments | Taxpayers who can pay eventually but need more time | Interest and penalties continue until paid off | Online, by phone or Form 9465 by mail |
| Offer in compromise | Allows you to settle your tax debt for less than you owe | Those facing financial hardship with limited ability to pay | Difficult to qualify and requires detailed financial disclosure | Online or Form 656 and Form 433-A (OIC) or 433-B (OIC) by mail |
| Penalty abatement | Removes eligible IRS penalties, but not the underlying tax or interest | Taxpayers with a clean compliance history or a valid reason for filing or paying late | Doesn't reduce the tax owed or most interest charges | By phone or written request to the IRS |
| Spousal relief | Removes responsibility for tax debt caused by a spouse’s error | Individuals unaware of errors on a joint return | Only applies in specific situations involving spousal liability | Form 8857 by mail |
| Currently not collectible status | Temporarily pauses IRS collection efforts | Taxpayers who can’t afford to pay basic living expenses | Debt is not forgiven and continues to accrue interest | By phone or by mail; Form 433-F, Form 433-A or Form 433-B typically required |
Payment plan (installment agreement)
If you can’t pay your tax bill in full, you can apply for an IRS payment plan, also known as an installment plan.
Short-term payment plan
If you owe less than $100,000 in combined taxes, penalties and interest, you may qualify for a short-term plan, which involves paying what you owe in 180 days or less.
Long-term payment plan
If you’ve filed all required returns and owe $50,000 or less in combined taxes, penalties and interest, you may qualify for a long-term payment plan, also known as a simple payment plan or installment agreement. The IRS states that 90% of individual taxpayers typically qualify for this plan.
The different types of long-term payment plans include:
Simple payment plan: Available to most taxpayers who owe $50,000 or less in combined tax, penalties and interest
Guaranteed installment agreement: Available if you owe $10,000 or less (excluding penalties and interest), have filed and paid on time for the past five years, haven't used an installment agreement before and can pay the balance within three years
Partial payment installment agreement: For taxpayers who can't pay their full tax debt; the IRS must review your financial documentation for approval and review your eligibility every two years to determine whether your financial situation has changed
Offer in compromise
The IRS also offers the option for an offer in compromise. This gives taxpayers the opportunity to pay less than they owe, discharging some of their debt. Typically, this option is available to people who can’t afford to pay or if paying would create a financial hardship.
When you apply, the IRS will assess your income, expenses, assets and overall ability to pay. A $205 application fee is required. Not every application is approved, but you can use the IRS offer in compromise prequalifier tool to check eligibility and program requirements.
Offer in compromise eligibility
To be eligible for an offer in compromise, you must meet certain requirements, such as:
You must have filed all required tax returns and made the required estimated payments. Or, if you’re an employer, you must have made all tax deposits for the current quarter and previous two quarters.
You are not in an open bankruptcy proceeding.
You must have a valid extension for the current year’s tax return.
An OIC review can take up to 24 months, depending on case complexity and inventory levels, according to the IRS. During the review, you may be asked to provide additional financial information before a decision is made. If the IRS can process your offer, they will send you a letter with the estimated date of contact.
Penalty abatement
Penalty abatement is when the IRS removes certain penalties if the taxpayer has a valid reason for failing to file or pay on time. It doesn’t reduce the tax you owe or the interest charged on that tax, but it can lower your overall balance by eliminating eligible penalties.
The two most common types of penalty abatement are:
First-time penalty abatement: To qualify, you’ll typically need to have filed all required returns and paid any tax due, and you can’t have had significant penalties in the previous three years.
Reasonable cause relief: This is available when circumstances beyond your control, such as a natural disaster, serious illness or death in the family, prevented you from meeting your tax obligations.
Spousal relief
The IRS allows for spousal relief if your spouse made errors on your tax return without you being aware. You’ll generally receive a mailed notice from the IRS that you owe money on a joint tax return. You must then follow the instructions provided and contact the IRS to inform them of the error.
There are two types of spousal relief:
Injured spouse relief: This option allows you to reclaim the money taken from your tax return and apply it to your spouse’s debts.
Innocent spouse relief: With this option, you don’t have to pay for additional federal income tax owed by your spouse as a result of errors on your joint tax return.
Currently not collectible status
Currently not collectible status is not a formal tax forgiveness program, but it may provide temporary relief if you’re unable to pay your tax debt due to financial hardship. When your account is placed in CNC status, collections will stop temporarily, though penalties and interest will continue to accrue.
To qualify, you must provide detailed financial information to the IRS so it can evaluate your income, expenses and assets. If you qualify, the IRS will typically reassess your financial situation in the future to reevaluate your eligibility.
» RELATED: Negotiate with the IRS on back taxes
How to apply for IRS tax forgiveness
You can apply for some types of IRS tax forgiveness through your online IRS account, such as a payment plan or an offer in compromise. Generally, here are the steps you’ll take:
Choose a program: Decide which option fits your situation, such as a payment plan, offer in compromise or CNC status.
Confirm eligibility: Make sure you’ve filed all required tax returns and meet basic IRS requirements for the program you’re interested in.
Gather financial documents: Collect details on your income, expenses, assets and debts.
Complete the application: Submit the required forms for the program you choose, either online or by mail.
Submit and follow up: Send your application and respond to any IRS requests for additional information.
Tax forgiveness by state
Pros and cons of IRS tax forgiveness
IRS tax forgiveness programs can make tax debt more manageable, but they aren't the right solution for everyone. Before applying, understand both the potential benefits and drawbacks.
Pros
- Settle tax debt for less than you owe
- Flexible payment plans and relief options
- May stop collections during financial hardship
Cons
- Strict eligibility requirements
- Application fees for some programs
- Interest and penalties may continue to accrue
Avoid IRS tax forgiveness scams
Scammers often pose as tax relief companies or even IRS agents to pressure consumers into paying for services they do not need or to hand over sensitive personal information. Some red flags to watch for when it comes to IRS tax forgiveness scams include:
Approval guarantees: The IRS does not guarantee approval for tax forgiveness. Avoid anyone who promises to settle your tax debt without reviewing your full financial situation.
Large upfront fees: Avoid companies that demand immediate payment and charge thousands of dollars in fees before doing any work.
Claims of new programs: Scammers often advertise so-called new IRS forgiveness programs. In reality, most relief options have strict eligibility rules and are not new.
High-pressure sales tactics: Avoid any companies that pressure you to act immediately.
Contact by phone or text: If you owe taxes, the IRS will contact you via a notice in the mail. It will not call or text you. You can also log in to your online account to view whether you owe taxes.
You can check if a tax relief company is legitimate by using the IRS Directory of Federal Tax Return Preparers to verify its credentials.
» RELATED: Best tax relief companies
When to file for bankruptcy
Although it’s not technically an IRS program, filing for bankruptcy effectively stops collection efforts for unpaid taxes. The two most common types of bankruptcy are Chapter 7 and Chapter 13:
Chapter 7 bankruptcy: This common form of bankruptcy uses assets like your car or home to resolve outstanding debt. Debt can be discharged in as little as three months when your income is below a certain point, as dictated by your state.
Chapter 13 bankruptcy: Chapter 13 bankruptcy, also known as a wage earner’s plan, allows you to pay off your debt in installments over time, typically over three to five years.
Be aware that bankruptcy can affect your credit score for up to 10 years, so it is highly recommended that you consult a bankruptcy or tax attorney to provide personalized advice based on your unique financial situation.
FAQ
What happens if my application for tax forgiveness is denied?
If your application for tax forgiveness is denied, you will receive a notice from the IRS explaining the reason and how to dispute the decision. For example, it might deny an application if you don’t meet eligibility requirements or if you have an income that’s too high, errors on your application or an incomplete application.
To check the status of your tax forgiveness application, you can go to the IRS website and log in to your online account for more details. You can also reach out to the IRS’s Independent Office of Appeals for additional assistance.
How much does the IRS usually settle for?
The IRS doesn’t settle for a standard amount, instead evaluating your income, allowable expenses and asset equity to determine the most it can reasonably collect. An offer in compromise must reflect your reasonable collection potential, so settlement amounts vary widely from case to case.
How hard is it to qualify for IRS tax forgiveness?
It is generally hard to qualify for IRS tax forgiveness since most programs require you to be fully compliant with filing requirements and to provide detailed financial documentation. Options like an offer in compromise have strict eligibility standards, and many applications are denied because the IRS determines the taxpayer can afford to pay through an installment agreement instead.
Can I qualify for tax forgiveness if I'm self-employed?
Yes, you can qualify for tax forgiveness if you’re self-employed as long as you meet the eligibility requirements. Depending on your situation, you may qualify for an installment agreement, an offer in compromise or CNC status.
What happens to penalties and interest during an installment agreement?
Penalties and interest during an installment agreement continue to accrue until the debt is paid in full. Making on-time payments and paying off your balance as quickly as possible can help reduce the total amount you owe.
What is IRS one-time forgiveness?
IRS one-time forgiveness typically refers to first-time penalty abatement, which is generally available to taxpayers with three years of compliance history. The IRS will review your account and support documentation to see if you qualify. You can call the IRS, or send a written statement or Form 843, to the IRS by mail.
What is the IRS Fresh Start program?
The IRS Fresh Start program doesn’t technically exist as an IRS program. Instead, this program name generally refers to the IRS’s tax relief programs, such as installment agreements and offers in compromise.
Article sources
ConsumerAffairs writers primarily rely on government data, industry experts and original research from reputable publications to inform their work. Specific sources for this article include:
IRS, “Get help with tax debt.” Accessed Oct. 7, 2026.
IRS, “Let us help you.” Accessed Oct. 7, 2026.
IRS, “Taxpayer Bill of Rights.” Accessed Oct. 7, 2026.
IRS, “Online payment agreement application.” Accessed Oct. 7, 2026.
IRS, “Penalty relief for reasonable cause.” Accessed Oct. 7, 2026.
IRS, “Administrative penalty relief.” Accessed Oct. 7, 2026.
IRS, “Offer in compromise.” Accessed Oct. 7, 2026.
IRS, “Tax relief for spouses.” Accessed Oct. 7, 2026.
IRS, “Injured spouse relief.” Accessed Oct. 7, 2026.
IRS, “Innocent spouse relief.” Accessed Oct. 7, 2026.
IRS, “Declaring bankruptcy.” Accessed Oct. 7, 2026.