Eligibility criteria for tax relief
At its core, IRS tax debt relief eligibility comes down to your income, your expenses and your assets. The IRS does not have standard guidelines for tax relief eligibility. Instead, it reviews your financial situation along with the amount of tax debt you owe.
You may qualify for some form of tax relief if:
- Your monthly income is not enough to cover basic living expenses and your full tax payment.
- You have limited equity in assets such as a home, vehicle or liquid savings.
- You experienced a significant hardship, such as a medical emergency, job loss or natural disaster.
- You or a dependent have a long-term disability, receive disability pensions or face elevated recurring medical expenses that affect your ability to pay.
- You are unable to pay your tax debt in full within a reasonable time frame.
- You are current on required tax filings or willing to become compliant.
Meeting one or more of these criteria does not guarantee approval, but it may indicate that you are a strong candidate for an IRS payment plan or other relief option.
The same tax debt relief options are available for both businesses and individuals, according to Stephen Weisberg, a lead tax attorney at The W Tax Group, a nationwide tax defense company. “That said, business relief is at times harder to come by depending on the status of the business and the relief requested. Both individuals and businesses are judged by their income, expenses and equity in assets,” he explained.
The IRS reviews how much monthly disposable income you have and how much you have in assets. This helps determine whether you can meet basic expenses while paying tax debt over time.
» LEARN: Best tax relief for seniors
What is reasonable collection potential?
Reasonable collection potential, or RCP, is the IRS’s calculation of how much it believes it can realistically collect from you. It plays a central role in an offer in compromise, which is a request to settle tax debt for less than the full amount owed.
RCP generally includes two main components:
- Your net equity in assets, including bank accounts, investments, real estate, vehicles and other property
- Your future income, after the IRS accounts for allowable living expenses
If your reasonable collection potential is equal to or greater than your total tax debt, the IRS will reject a settlement offer. If your RCP is lower than your total balance, an offer in compromise may be more realistic, though it is still not guaranteed.
» LEARN: How does tax relief work?
Establishing reasonable cause for tax relief
If you can’t manage your tax debt due to circumstances beyond your control — a catastrophic medical situation or a natural disaster, for example — the IRS may be willing to relieve part of your tax burden. You’ll have the burden of proving what the IRS defines as “reasonable cause.”
Financial hardship can help explain why you couldn’t pay, but it does not automatically establish reasonable cause. For example, a taxpayer earning $30,000 per year with $50,000 in tax debt and minimal assets presents a stronger hardship case than someone earning $120,000 per year with the same balance due.
The same principle can apply to a small business owner with $80,000 in annual net income and $150,000 in tax debt, who may qualify for partial payment options if business expenses and secured debts significantly reduce available cash flow.
Documentation is important to support a reasonable cause claim: Medical bills, termination notices, insurance claims, bank statements and proof of monthly expenses can help support your request.
» MORE: Tax relief statistics
Types of tax relief available
The right type of tax relief for you depends on your unique financial position and your situation with the IRS. For back taxes, the most common IRS options are installment agreements, partial pay installment agreements, offers in compromise, currently not collectible status and penalty abatements.
» MORE: Types of innocent spousal relief
Installment agreements
An installment agreement is an IRS payment plan that lets you pay your balance over time through fixed monthly payments, typically over 72 months (six years). It keeps your account in good standing and stops aggressive collection actions, but interest and standard late-payment penalties continue to accrue until the balance is paid off.
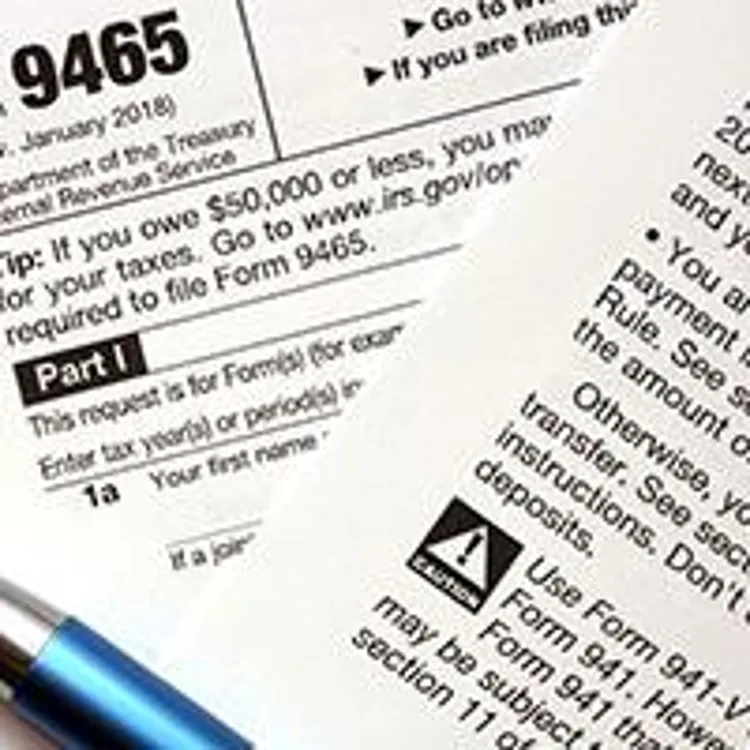
As of 2026, the IRS offers Simple Payment Plans to qualifying taxpayers who owe less than $50,000 in combined tax, penalties and interest and can pay within the collection period (generally 10 years from the assessment date).
» MORE: Pros and cons of IRS payment plans
Partial pay installment agreements
A partial pay installment agreement is for those who can make monthly payments but cannot reasonably pay the full balance before the collection period expires. The IRS reviews your income, allowable expenses and asset equity before approving this type of agreement.
Offer in compromise (OIC)
An offer in compromise lets eligible taxpayers settle their tax debts for less than the full amount owed. To be eligible to apply, an individual must generally have filed all required tax returns, made required estimated-tax payments and not be in an open bankruptcy proceeding.
This is one of the best-known forms of tax relief, but it’s not the best fit for everyone. If the IRS determines you can pay the full balance through assets or a payment plan, it’s unlikely to accept an OIC.
Currently not collectible (CNC) status
This type of tax relief is reserved for situations of severe financial hardship. For CNC status, your monthly expenses must exceed your income, and you cannot have significant equity in assets, Weisberg said.
“If you have a serious situation where you would not be able to pay your household bills if you had to pay the IRS, you may qualify for a currently not collectible status,” Weisberg said. “You are protected from IRS collections and not required to pay the IRS anything.”
While in CNC status, the IRS temporarily halts levies and garnishments. Interest and penalties continue to accrue, though, and the IRS can periodically review your finances and restart collections later if your financial circumstances improve.
Penalty abatement
Penalty abatement allows you to request a reduction or removal of IRS penalties, like those assessed for failing to file and/or pay your taxes by the deadline. Both first-time penalty abatement and a reasonable cause penalty abatement require you to provide proof of financial difficulty in order for your request to be accepted.
| Installment agreement | Partial pay installment agreement | Offer in compromise | Currently not collectible | Penalty abatement | |
|---|---|---|---|---|---|
| Who qualifies | Taxpayers who can pay over time but not in full immediately | Taxpayers with limited ability to pay full balance before collection period ends | Taxpayers who cannot reasonably pay full amount owed | Taxpayers experiencing severe financial hardship | Taxpayers with reasonable cause or first-time penalty history |
| Income requirement | Must have enough disposable income to make monthly payments | Income does not fully cover debt within repayment window | Disposable income is insufficient to pay debt in full | Monthly expenses exceed income | Not strictly income-based, but hardship may support request |
| Asset consideration | Assets are reviewed if balance is high or financial disclosure is required | IRS reviews equity in assets and overall ability to pay | Equity in assets is closely evaluated | Little to no significant equity in assets | Asset review typically not central unless tied to hardship claim |
| Best for | Those who need more time to pay a manageable balance | Those with long-term financial constraints | Those facing significant hardship with limited assets | Those unable to pay anything without missing basic living expenses | Those seeking removal or reduction of IRS penalties |
Who qualifies for the IRS Fresh Start Program?
The IRS Fresh Start Program expanded eligibility for installment agreements and offers in compromise, making it easier for taxpayers experiencing financial hardship to qualify for relief. While the initiative does not eliminate tax debt outright, it broadened access to manageable payment options and settlement opportunities.
Under changes to the Fresh Start Program, the IRS increased the debt threshold for streamlined installment agreements. Taxpayers who owe below a certain amount may qualify for a payment plan without submitting extensive financial documentation. These streamlined plans typically allow repayment over several years, making them more accessible for individuals and small businesses with moderate balances.
The “Fresh Start Program” is an informal label for IRS collection policy changes and options, not a separate application that automatically forgives debt.
To qualify for Fresh Start Program relief, you must be current on all required tax filings. This means filing all past-due returns before applying for an installment agreement or offer in compromise. The IRS will not approve most relief options if you are not in compliance with your filing obligations.
Meeting these requirements does not guarantee approval, but taxpayers who demonstrate financial hardship, fall within applicable debt thresholds and remain compliant with filing requirements may benefit from the expanded relief options introduced under the Fresh Start Initiative.
How to apply for tax relief
To work directly with the IRS on a tax relief payment plan, you can apply on the IRS website or visit your local Taxpayer Assistance Center (find it here). While simple requests to extend the payment deadline can move relatively quickly, a more complicated request, such as an offer in compromise, could take six months or more to process, Weisberg said. Instead of working directly with the IRS, you could contact a tax attorney or work with a tax relief company.
4 common misconceptions about tax relief
Below, we’ll take a look at some of the most pervasive myths you might have in your mind if you plan to approach the IRS about relieving or reducing your tax burden.
1. MYTH: Seeking tax relief will get you out of paying taxes
This is only true in very few cases. Most forms of tax relief from the IRS come in the form of extending the amount of time you have to pay your tax debt, reducing or eliminating penalties due to hardship or negotiating settlements if you have a severe and enduring financial difficulty.
2. MYTH: The only way to get tax relief is to go directly to the IRS
There’s logic in going directly to the source — the IRS — in order to tackle tax debt. But if you don’t feel comfortable doing that, a tax attorney can help you make your case for reasonable cause or support you in determining your best course of action. There are plenty of tax relief companies to choose from that can help you negotiate tax relief with the IRS.
3. MYTH: Filing for bankruptcy will eliminate your tax debt
Most people are under the impression that bankruptcy solves all financial woes. In reality, there are strict rules about which tax debts can be discharged in Chapter 7 or Chapter 13 bankruptcy. It's important to note that recent tax debts are very rarely discharged.
4. MYTH: Your tax debt will eventually go away if you ignore it
This is never the case. Ignoring your tax debt will only ensure one thing: Your tax bill will continue to grow. When you fail to file or pay your taxes and don’t seek some sort of resolution or negotiation with the IRS, it will continue to assess penalties on your account.
These penalties and fees grow steeper the longer you let the problem persist. They can even turn into wage garnishments and the eventual seizure of your assets.
» RELATED: How to file back taxes
FAQ
Are there any state-specific tax relief programs?
Although some programs overlap, each state has its own set of rules regarding tax debt relief, according to Weisberg. “Many states have a monthly payment program, a hardship status, and a program that's equivalent to the offer in compromise. But it varies state by state,” he said. There's not a one-stop shop for finding state tax relief options, but most tax attorneys can help.
What is the difference between tax relief and tax evasion?
Tax relief is a way for a taxpayer to receive assistance with their tax debt rather than paying the entire amount owed all at once. Tax evasion is completely different. Tax evasion is when you deliberately and fraudulently do not pay your taxes.
What happens if my tax relief application is denied?
You always have the option to reapply for tax relief if your application is denied by the IRS. You may also consider applying for a lesser amount of relief. For instance, instead of applying for an offer in compromise, consider asking the IRS for a payment plan you can manage.
Can low-income taxpayers qualify for tax relief?
Yes. Low-income taxpayers often have a stronger case for certain types of relief, especially if they cannot cover basic living expenses while paying their tax debt. The IRS reviews income, allowable expenses and assets to determine eligibility for options such as currently not collectible status or an offer in compromise.
Working taxpayers with low to moderate earned income may qualify for the Earned Income Tax Credit, or EITC. The EITC is a refundable credit based on earned income, filing status and, when applicable, qualifying children. Because it can reduce tax owed and may generate a refund for eligible taxpayers, it can lessen or eliminate the need for debt relief.
Can businesses qualify for tax relief?
Yes, businesses can qualify for many of the same tax relief options available to individuals, including installment agreements and offers in compromise. However, eligibility depends on the business’s income, expenses, assets and compliance with filing requirements.
Does the IRS forgive tax debt?
In limited circumstances, the IRS may agree to settle tax debt for less than the full amount owed through an offer in compromise. However, most tax relief options do not eliminate the underlying tax debt. Instead, they provide extended payment terms, temporary collection pauses or penalty reductions based on financial hardship.
Article sources
ConsumerAffairs writers primarily rely on government data, industry experts and original research from reputable publications to inform their work. Specific sources for this article include:
- Internal Revenue Service, “Get Help With Tax Debt.” Accessed Aug. 26, 2026.
- Internal Revenue Service, "Payment Plans; Installment Agreements." Accessed Aug. 26, 2026.
- Internal Revenue Service, "Earned Income Tax Credit (EITC)." Accessed Aug. 26, 2026.
- Federal Trade Commission, “Trouble Paying Your Taxes?” Accessed Aug. 26, 2026.
- Internal Revenue Service, “Penalty Relief.” Accessed Aug. 26, 2026.
- Internal Revenue Service, “Offer in Compromise.” Accessed Aug. 26, 2026.